
The 2026 Luxury Fracture: How Portfolio Liquidations and Algorithmic Pricing Are Rewiring the Prestige Economy

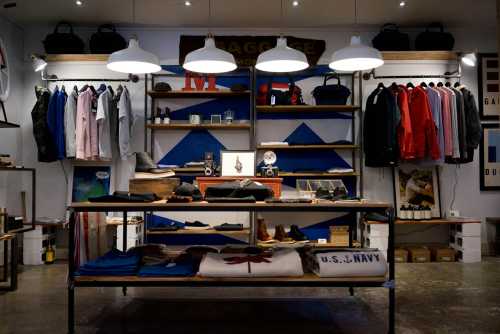
Managing a modern luxury conglomerate is akin to operating a high-stakes casino where the house is systematically raising the minimum bet while simultaneously selling off the peripheral gaming tables to focus solely on the VIP rooms. The margin for brand dilution has vanished, and the financial instruments governing prestige are giving conflicting readings.
The September Inflection Point
In September 2026, the global luxury sector reached a definitive inflection point as major conglomerates initiated a structural portfolio sell-off while simultaneously executing aggressive price hikes to offset volume declines in key Asian markets. This dual strategy marks the end of the democratization era and the beginning of ruthless margin extraction, fundamentally altering how prestige is valued, distributed, and consumed.
The Algorithmic Squeeze on Aspirational Consumers
Mainstream coverage frequently celebrates the resilience of heritage luxury houses, framing recent price increases as a triumph of brand equity and exclusivity. However, this narrative obscures a systemic reality: the weaponization of pricing power to mask severe volume contraction among the middle class. According to a Q3 2026 Bain & Company luxury market report, entry-level luxury goods have seen an average price increase of 18% year-over-year, while transaction volumes in the aspirational segment contracted by 12%. The unseen implication is the profound bifurcation of the consumer base. When a conglomerate raises the price of an entry-level handbag by 20% to protect margins, it effectively prices out the aspirational buyer, transforming luxury from an attainable reward into an exclusionary asset class. This hollows out the foundational tier of the brand's customer lifecycle, starving the house of the next generation of loyal, high-lifetime-value clients.
The Compliance Cost of Circular Ambitions
Simultaneously, the broader luxury ecosystem is fracturing under the weight of aggressive regulatory scrutiny regarding supply chain transparency. The impending enforcement of the EU Digital Product Passport (DPP) mandates comprehensive, blockchain-verified traceability for all textile and leather goods entering the European market. While policymakers frame this as an unambiguous environmental victory, the operational reality is a massive financial burden. As noted in a 2026 EU regulatory impact assessment, the capital expenditure required for DPP compliance threatens to consume up to 8% of operating margins for mid-tier luxury houses. Mega-conglomerates like LVMH can absorb these costs as a competitive moat, while independent, heritage-focused ateliers are forced into precarious mergers or face market exit entirely due to the prohibitive cost of adherence.
The Secondary Market Arbitrage
Beyond primary retail, the authenticated resale market is actively cannibalizing entry-level luxury sales. As primary prices skyrocket, consumers are increasingly turning to verified secondhand platforms to acquire heritage pieces at a fraction of the cost. This creates a secondary market arbitrage opportunity that legacy brands are struggling to control. By failing to integrate circular economy models into their primary business strategies, luxury houses are inadvertently ceding the entry-level market to third-party platforms that capture the margin on the second, third, and fourth sales of a single garment. The brand retains the cultural cachet, but the financial yield is increasingly captured by digital intermediaries.
The Exclusivity Defense Fallacy
Proponents of the current pricing strategy argue that aggressive price hikes are a necessary mechanism to protect brand equity and maintain the aura of exclusivity. They contend that by shedding price-sensitive, aspirational consumers, luxury houses can focus their resources on ultra-high-net-worth individuals who are immune to macroeconomic volatility. While technically accurate regarding short-term margin protection, this perspective conflates exclusivity with long-term viability. Luxury goods exhibit highly inelastic demand curves among the ultra-wealthy, but this demographic is finite. By systematically alienating the aspirational middle class, brands are burning the bridge to their future top-tier clients, risking a generational gap in brand loyalty that no amount of VIP clienteling can repair.
The Heritage Moat Myth
A secondary counter-argument posits that true heritage brands possess an impenetrable moat, rendering them immune to the cyclical downturns that plague mid-market fashion. Advocates for this view argue that the historical prestige of houses like Hermès or Chanel ensures perpetual demand, regardless of price elasticity or regulatory friction. Yet, this view ignores the macroeconomic reality of shifting cultural capital. The next generation of high-net-worth individuals increasingly prioritizes experiential value, ethical provenance, and digital innovation over legacy logos. Heritage alone is no longer a sufficient safeguard against declining relevance if the brand fails to adapt its narrative to the values of emerging wealth demographics.
Echoes of the 2008 Post-Lehman Contraction
To understand the current trajectory, one must examine the structural shifts following the 2008 global financial crisis. During that era, luxury conglomerates faced a severe liquidity crunch and responded by aggressively slashing wholesale distribution, closing secondary-tier boutiques, and tightening control over their supply chains. The lesson from that period is that transitional pain, if leveraged correctly, permanently alters the industry's power dynamics in favor of the most capitalized players. Just as the post-2008 landscape marginalized independent luxury brands and cemented the dominance of the mega-conglomerates through direct-to-consumer consolidation, the 2026 regulatory and pricing squeeze will accelerate a similar extinction event for mid-tier heritage houses unable to absorb the compliance and margin costs.
Strategic Posture for the Micro-Economy
For local businesses and citizens, navigating this landscape requires immediate strategic recalibration. Independent luxury retailers and vintage curators must pivot toward hyper-specialized authentication and provenance services, offering verifiable history that mass-market platforms cannot replicate. Citizens and consumers should treat luxury purchases not as discretionary spending, but as alternative asset classes. Rigorously auditing the secondary market value of a piece before purchase, and demanding granular supply chain data to ensure DPP compliance, transforms a depreciating consumer good into a verifiable, liquid asset. Furthermore, local hospitality venues catering to high-net-worth individuals must integrate exclusive, non-replicable experiential programming that aligns with the shifting values of the new luxury consumer.
The 2027 Bifurcation Horizon
Looking six months ahead, the luxury landscape will undergo definitive structural bifurcation. By early 2027, expect the first major regulatory fines levied against mid-sized luxury brands for non-compliance with digital product passport data standards, accelerating a wave of distressed acquisitions by well-capitalized conglomerates. Simultaneously, the market will split into two distinct tiers: a hyper-exclusive, human-curated heritage tier reserved for ultra-high-net-worth clients, and a mass-market tier dominated by "luxury-adjacent" synthetic goods and authenticated secondhand platforms. The era of frictionless, aspirational luxury expansion is concluding, replaced by a landscape defined by strict regulatory compliance, verifiable provenance, and a stark valuation gap between authentic historical craftsmanship and algorithmic trend replication.
Related Articles
The Margin Squeeze: How Regulatory Realignment Is Forcing a Structural Reset in U.S. Healthcare
Sep 14, 2026
The Margin Squeeze: How Regulatory Friction and Algorithmic Mandates Are Rewiring Healthcare Economics
Sep 14, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account