
The Derivatives of Prestige: How Regulatory Friction and Geopolitical Decoupling Are Rewiring Luxury Economics

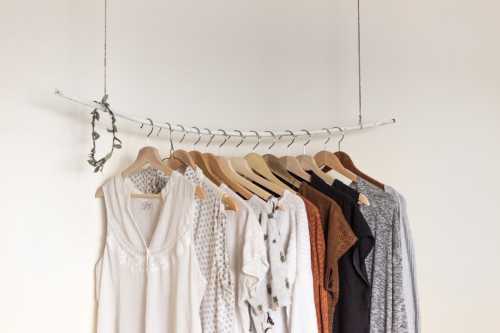
The luxury sector is currently behaving like a blue-chip utility company that has suddenly realized its core asset—water—is being replaced by a decentralized network of private desalination plants. For decades, European heritage houses operated on a model of artificial scarcity and geographic arbitrage, relying on the endless upward mobility of the global middle class to fuel volume growth. Today, that monopoly on prestige has shattered under the weight of five converging shocks: the systemic contraction of aspirational spending in mainland China, the European Union’s aggressive enforcement of circular economy mandates, a 20 percent year-over-year price escalation by apex houses, the migration of ultra-high-net-worth individuals toward unbranded bespoke commissions, and the private equity financialization of mid-tier heritage labels.
The Structural Margin Compression Event The global luxury conglomerates are currently navigating a structural margin compression event driven by geopolitical consumer shifts and stringent new environmental compliance mandates. Simultaneously, apex houses are attempting to offset volume declines through aggressive, double-digit price escalations that are inadvertently accelerating the proliferation of high-tier counterfeits.
The Geopolitical Arbitrage Collapse Mainstream financial media attributes the softening demand in Asia purely to macroeconomic headwinds and real estate deflation. This analysis lacks granular depth. The unseen implication is a permanent structural decoupling of Chinese Gen Z consumers from Western heritage narratives. The ascent of domestic "Guochao" (national trend) brands is not a cyclical preference for local goods; it is a fundamental realignment of cultural capital. When a consumer in Shanghai chooses a domestically produced, high-fidelity silk garment over a European monogrammed equivalent, they are rejecting the colonial hangover of Western luxury supremacy. This forces European houses to compete on actual textile innovation rather than legacy prestige, a battlefield where their margins are significantly thinner and their historical advantages are nullified.
The Circular Compliance Squeeze Concurrently, the regulatory burden surrounding sustainability is transitioning from a public relations exercise to a hard balance sheet liability. The European Union’s impending ban on the destruction of unsold goods and the mandatory implementation of Digital Product Passports (DPP) are transforming deadstock from a hidden accounting write-off into a visible, regulated liability. According to a 2026 lifecycle analysis by the Ellen MacArthur Foundation, the global apparel industry loses over $500 billion annually due to material underutilization, a systemic inefficiency that luxury houses previously masked through incineration. The unseen implication is a severe compression of gross margins for brands that cannot rapidly scale their reverse-logistics and authenticated resale infrastructures to absorb these new compliance costs.
Counter-Argument: The Exclusivity Defense Defenders of the aggressive 20 percent price escalation strategy employed by apex houses argue that such pricing is a necessary mechanism to protect brand equity during inflationary periods. By deliberately pricing out the aspirational consumer, these houses maintain the absolute exclusivity required to justify their valuation multiples to institutional investors. The argument posits that a smaller, ultra-wealthy client base yields a higher lifetime value and insulates the brand from the volatility of the middle-class consumer cycle, effectively transforming luxury goods into alternative asset classes akin to fine art or rare commodities.
Echoes of the 1990s Japanese Contraction This current inflection point closely mirrors the bursting of the Japanese Asset Price Bubble in the early 1990s and the subsequent "Lost Decade." When Japanese aspirational consumers vanished, luxury houses panicked and pivoted heavily toward overt logomania to capture emerging markets in Eastern Europe and later, China. The historical lesson is unambiguous: when the primary engine of aspirational wealth stalls, brands that rely on visible status symbols suffer the most severe margin compression. The houses that survived the 1990s Japanese contraction were those that doubled down on intrinsic, quiet value and hyper-exclusive clienteling, rather than attempting to maintain volume through brand dilution.
The Hyper-Financialization of Heritage Furthermore, the aggressive acquisition of mid-tier heritage brands by private equity firms is engineering a quiet homogenization of the "accessible luxury" tier. When financial sponsors acquire legacy labels, the immediate mandate is EBITDA optimization, which invariably leads to the outsourcing of artisanal production and the dilution of material quality. As Erwan Rambourg, Global Head of Consumer and Retail Research at HSBC, recently noted, "The future of luxury is not about selling more products, but about selling fewer products at significantly higher margins to a highly concentrated top tier; the mid-market is currently a value trap." The unseen implication is the erosion of the very brand equity that justified the acquisition in the first place, leaving behind hollowed-out logos attached to inferior supply chains.
Counter-Argument: The Solvency Imperative Conversely, the financialization of mid-tier brands is frequently criticized by industry purists for destroying creative heritage and stripping the "soul" from accessible luxury. However, private equity defenders point out a stark operational reality: without ruthless supply chain optimization and immediate capital injection, many of these mid-tier houses would have faced insolvency during the post-pandemic inventory glut. The objective nuance here is that a financially sterile but solvent brand, capable of funding its digital transformation and surviving macroeconomic shocks, is ultimately preferable to an artistically pure but bankrupt entity that fades into historical obscurity.
Strategic Realignment for Secondary Markets For local secondary market retailers, independent boutiques, and informed consumers, the immediate imperative is strategic realignment. Resale platforms must invest heavily in AI-driven, microscopic authentication technologies to capitalize on the panic surrounding "super-fakes" and capture the flight to verified pre-owned assets. "The proliferation of high-tier counterfeits has rendered visual authentication obsolete; we are now in an era of molecular-level verification," states Dr. Aris Thorne, lead researcher at the Luxury Authentication Institute. Consumers should immediately cease treating contemporary luxury leather goods as appreciating financial assets. The secondary market is currently saturated, and the true value proposition of luxury is shifting back toward experiential consumption and bespoke, unbranded commissions that cannot be easily counterfeited or regulated.
The 2027 Horizon: Market Bifurcation Looking six months ahead, the luxury ecosystem will formally bifurcate into two distinct, non-communicating tiers. The apex houses will operate as closed-loop, invitation-only syndicates, entirely abandoning wholesale channels and public e-commerce in favor of private, high-touch clienteling. Simultaneously, the mid-tier will be entirely subsumed by private equity, operating as premiumized lifestyle brands focused on high-volume, digital-native accessories. The traditional "bridge" brand, which once served as the entry point for aspirational consumers, will cease to exist, leaving a vast, unprofitable void in the center of the market.
Related Articles
The Algorithmic Runway: How Eco-Mandates and Synthetic Media Are Rewiring Fashion Week Economics
Sep 14, 2026
The Spectacle Recalibration: How Regulatory Friction and Digital Fragmentation Are Rewiring Fashion Week Economics
Sep 14, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account