
The Valuation Reckoning: Structural Realignment in the Global Streetwear Economy

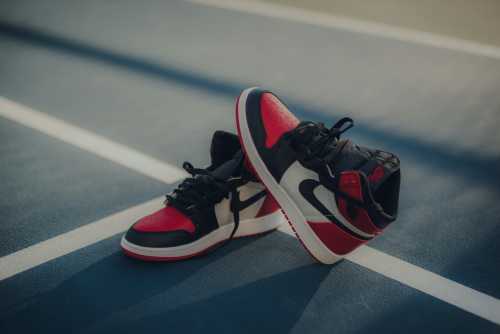
Managing the modern streetwear industry is akin to trading unregulated derivatives on a decentralized exchange: the outward presentation is curated and exclusive, but the underlying mechanics are driven by ruthless algorithmic arbitrage, volatile supply chain leverage, and the constant threat of regulatory margin compression.
The Valuation Reckoning: Supreme's $600 Million Write-Down
The core event defining the current streetwear landscape is a massive valuation correction, highlighted by VF Corporation’s $1.5 billion sale of Supreme to EssilorLuxottica, representing a $600 million loss from its 2020 acquisition price [[18]]. Concurrently, the industry is grappling with the maturation of the sneaker resale market, stringent regulatory crackdowns on sustainability claims, and the rapid infiltration of generative AI into design workflows. This convergence signals a definitive pivot from an era of unchecked hype-driven expansion to a highly regulated, margin-focused operational reality.
The Algorithmic Atelier: AI Design and the Authenticity Crisis
The integration of artificial intelligence into streetwear design is creating a profound trust deficit among core demographics. Driven by the desire to reduce sampling costs and accelerate time-to-market, corporate adoption of synthetic design tools is accelerating rapidly. Primary research indicates that generative AI models already hold around 45-50% of the overall AI-generated fashion market in 2025 [[42]]. The hidden consequence is a severe degradation of subcultural authenticity. When audiences realize that the "limited edition" graphic tees and complex patterns are the output of a server farm rather than independent human artistry, the foundational premise of streetwear's cultural capital collapses. This dynamic effectively neutralizes the core value proposition of the genre, reducing heritage brands to highly controllable digital billboards that yield high impression metrics but abysmal long-term brand loyalty.
Critics frequently argue that the aggressive integration of generative AI into streetwear design will inevitably strip the industry of its tangible, human-driven cultural resonance and render independent creators obsolete. However, this perspective overlooks the baseline economic realities of modern apparel production. As industry analysts note, even imperfect AI-generated images help teams reach a shared understanding of design intentions rapidly [[41]]. By leveraging AI for rapid prototyping and pattern generation, emerging streetwear labels can bypass prohibitive sampling costs, democratizing access to high-quality design tools that were previously monopolized by legacy conglomerates.
The Hype Evaporation: Sneaker Resale Market Maturation
Mainstream financial coverage routinely celebrates the sneaker resale market as a guaranteed alternative asset class, pointing to aggregate growth projections. However, this macro-level optimism masks a severe margin compression occurring beneath the surface for mid-tier releases. While the global sneaker resale market is pegged between $6.5 billion and $10.6 billion for 2025, the hype bubble has effectively evaporated for anything outside of ultra-rare, legacy collaborations [[20]], [[26]]. The unseen implication is a liquidity crisis for platforms like StockX and GOAT, which built their valuation multiples on the assumption of perpetual, exponential volume growth. As consumer sentiment shifts toward practical, everyday footwear, these platforms are forced to diversify into apparel and accessories, diluting their core competency and exposing them to the same inventory risks that plague traditional retail.
The Compliance Trap: Greenwashing Penalties in Streetwear
Simultaneously, the regulatory environment surrounding fashion sustainability is shifting from voluntary corporate social responsibility pledges to enforceable legal mandates. Under the 2026 Green Claims Directive, vague sustainability claims carry concrete penalties, directly targeting the seasonal fast-fashion and streetwear cycles [[28]]. The hidden consequence of this policy shift is a massive compliance overhead for independent designers. While legacy conglomerates can absorb the cost of third-party lifecycle assessments and legal audits, smaller houses face prohibitive barriers to entry. This regulatory friction will act as a moat, consolidating market share exclusively among mega-corporations with deep research and development pockets, while forcing innovative but undercapitalized brands into obscurity or acquisition.
Some industry defenders argue that stringent regulatory enforcement against vague "eco-friendly" marketing claims will stifle indie brand innovation and burden small streetwear formulators with prohibitive compliance costs. Yet, this viewpoint dangerously underestimates the macroeconomic reality of consumer trust. Unregulated sustainability claims inherently destroy the provenance required for any premium transaction to occur. Establishing strict liability frameworks is not an impediment to innovation; rather, it is a pragmatic prerequisite for sustainable market adoption, ensuring that the industry does not collapse under the weight of its own fraudulent output.
Echoes of the Dot-Com Bubble: The Historical Precedent
To understand the trajectory of this market correction, one must examine the late 1990s dot-com bubble and the subsequent collapse of overvalued lifestyle brands. During that era, massive conglomerates acquired vast arrays of niche, subcultural labels, promising increased efficiency and diverse distribution. Instead, it triggered severe homogenization, where high-risk, innovative projects were systematically defunded in favor of safe, mass-market apparel that ultimately stifled organic growth. The current consolidation of streetwear assets and resale platforms is following an identical trajectory, proving that without proactive antitrust oversight, the ecosystem will devolve into a sterile, corporate-controlled monoculture where independent innovation is acquired and shelved rather than nurtured.
Strategic Imperatives for Market Participants
Local streetwear retailers and independent designers must immediately decouple their revenue models from reliance on single-platform algorithmic distribution and vague "sustainable" marketing. Instead, they should capitalize on owned-and-operated channels, leveraging direct-to-consumer community platforms and verifiable, third-party audited supply chain transparency. For citizens and retail investors, the imperative is rigorous digital skepticism: treat viral sneaker drops and influencer endorsements with forensic scrutiny, recognizing that the current valuation of hype-driven brands is heavily inflated by speculative multiples rather than sustainable, long-term unit economics.
The Six-Month Horizon: Consolidation and Correction
Within the next six months, the streetwear ecosystem will face a definitive regulatory and operational correction. Expect the Federal Trade Commission and European authorities to finalize stringent guidelines targeting unsubstantiated "green" claims, triggering immediate operational friction for brands relying on superficial sustainability marketing. Concurrently, the market will witness its first major wave of distressed asset acquisitions, as mid-tier streetwear labels facing severe compliance liabilities and declining resale valuations are absorbed by mega-conglomerates at distressed valuations. The overarching landscape will pivot from a growth-at-all-costs attention gold rush to a highly regulated, trust-based ecosystem where verifiable cultural authenticity and strict regulatory compliance dictate market survival.
Related Articles
The Valuation Correction: How Financial Ceilings and Algorithmic Disruption Are Rewiring Global Football
Sep 14, 2026
The Margin Call: How Regulatory Friction and Asset Inflation Are Rewiring Global Football Economics
Sep 14, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account