
The Metabolic Reckoning: How GLP-1 Adoption and Regulatory Friction Are Rewiring the Fitness Economy

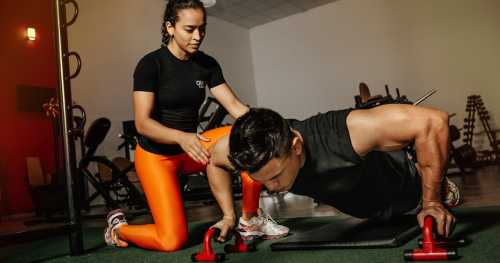
Think of the modern nutrition and fitness industry as a municipal water system that spent decades selling bottled water at a premium, only to suddenly discover the reservoir is being chemically altered by a new class of compounds, forcing a complete, involuntary overhaul of the purification infrastructure.
The Paradigm Shift in Metabolic Fitness
In 2026, the convergence of widespread GLP-1 medication adoption, aggressive FDA regulatory crackdowns on dietary supplements, and mandated corporate wellness ROI metrics has fundamentally destabilized the traditional fitness and nutrition landscape. This triad of forces is transitioning the sector from a volume-driven consumer goods model to a highly regulated, outcomes-based healthcare adjunct, rendering legacy business models obsolete.
The Hidden Economics of the "Gym-as-Clinic" Model
Mainstream media frames the rise of GLP-1 medications as a simple weight-loss trend, ignoring the profound structural shift it imposes on the fitness industry. Rapid pharmacological weight loss inherently includes the depletion of lean muscle mass, creating an urgent, secondary market for specialized metabolic conditioning. Recent data indicates that 35% of GLP-1 users now hold gym memberships, a significant increase driven by the clinical necessity of muscle preservation [[3]]. Consequently, fitness clubs are pivoting to become health platforms, with major operators like Planet Fitness partnering directly with telehealth providers to integrate prescription access into the membership ecosystem [[9]]. As clinical studies note, "exercise should play an essential role in helping patients and health systems maximize the long-term benefits" of these drugs [[7]]. Gyms are no longer selling access to equipment; they are selling clinical risk mitigation, fundamentally altering their liability and operational frameworks.
The Regulatory Squeeze on Supplement and Tech Claims
Simultaneously, the FDA is intensifying its oversight of the dietary supplement industry, targeting tainted products and advancing mandatory listing requirements to close historical loopholes [[59]]. This is a direct response to a market where over 75% of American adults use dietary supplements, yet under the 1994 DSHEA law, the FDA does not approve supplements for safety or effectiveness before they reach the market [[57]]. The FDA’s 2026 priority deliverables explicitly target the protection of consumer health through stricter enforcement, signaling an end to the era of unverified botanical and metabolic claims [[56]]. This regulatory friction will force a massive consolidation in the supplement market, wiping out marginal brands that cannot afford the new compliance overhead, much like the agency's recent determinations that certain compounds, such as kratom, cannot be lawfully marketed as dietary supplements [[64]].
The Corporate Wellness Mandate
Parallel to these shifts, corporate wellness has transitioned from a peripheral human resources perk to a mandated financial strategy. Industry data reveals that workplace wellness programs now demonstrate an average 6:1 return on investment, driven by quantifiable reductions in absenteeism and lower healthcare premiums [[42]]. Consequently, employers are demanding granular, wearable-derived biometric data to validate these returns. This effectively turns employee health metrics into corporate balance sheet assets, forcing a collision between personal privacy and fiduciary duty that the current legal framework is ill-equipped to handle.
The Democratization Myth in Wearable Biometrics
Proponents of wearable fitness technology argue that continuous biometric tracking democratizes health data, empowering individuals to make informed lifestyle choices without expensive medical consultations. However, this perspective is dangerously one-sided. It ignores the severe accuracy disparities across consumer device tiers and the stark lack of standardized clinical validation for metrics like continuous glucose monitoring or advanced sleep staging in non-medical devices. When consumer-grade wearables produce false positives or inaccurate metabolic readings, they do not democratize health; they medicalize anxiety and shift diagnostic liability onto an unregulated hardware ecosystem.
The False Premise of Inevitable Plant-Based Dominance
Industry advocates frequently project that the plant-based protein market will inevitably capture dominant market share from traditional animal agriculture, citing projections of expansion to $59.4 billion by 2036 [[29]]. This argument fails to account for the recent, severe market correction and consolidation in the alternative protein sector. The ongoing "alt-meat" slump has proven that consumer demand is highly elastic and acutely sensitive to price and texture parity, with growth now isolating to specific, functional niches like protein-fortified beverages rather than representing a wholesale dietary replacement [[34]]. Assuming inevitable dominance ignores the fundamental unit economics of food production.
Echoes of the Late 1990s Supplement Reckoning
This regulatory and structural inflection point mirrors the dietary supplement industry’s reckoning in the late 1990s following the ephedra crisis. At that time, the FDA’s eventual imposition of stricter manufacturing, labeling, and adverse event reporting standards decimated hundreds of fly-by-night operators. However, it simultaneously legitimized the surviving, compliant enterprises, transforming the sector from a fringe market into a respected component of the broader healthcare economy. The historical lesson is clear: regulatory friction acts as a competitive moat. The companies that survive the 2026 supplement and wearable crackdowns will not necessarily be the most innovative, but the most capitalized and compliant.
Strategic Imperatives for Industry Stakeholders
For local fitness businesses, the immediate imperative is to pivot programming toward resistance training and metabolic health coaching, explicitly marketing to the GLP-1 demographic’s clinical need for muscle preservation. For citizens and consumers, navigating this landscape requires demanding third-party certification (such as NSF or USP) for any dietary supplement and treating wearable biometric data as directional rather than strictly diagnostic. For corporate leaders, wellness investments must be tied to specific, measurable health outcomes rather than vague engagement metrics to satisfy the new, stringent ROI mandates.
The Six-Month Horizon: Bifurcation and Compliance
Looking six months ahead, the nutrition and fitness landscape will experience acute bifurcation. We will see a wave of mergers and acquisitions as mid-tier supplement brands are absorbed by legacy pharmaceutical or large consumer packaged goods companies capable of absorbing the new FDA compliance costs. Simultaneously, the "gym-as-clinic" model will face its first major legal challenges regarding the scope of practice, as fitness trainers inadvertently cross into unlicensed medical advice while guiding GLP-1 patients. The industry will not collapse, but it will permanently shed its unregulated, wild-west identity in favor of a highly scrutinized, clinically adjacent operational model.
Related Articles
The Metabolic Reckoning: How GLP-1s, UPF Regulation, and Biometric Data Are Rewiring Fitness
Sep 18, 2026
The Metabolic Recalibration: How September 2026 Exposed the Structural Fragility of the Wellness Industry
Sep 18, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account