
The Speculative Asset Trap: How Resale Markets and Regulatory Shifts Are Fracturing Streetwear

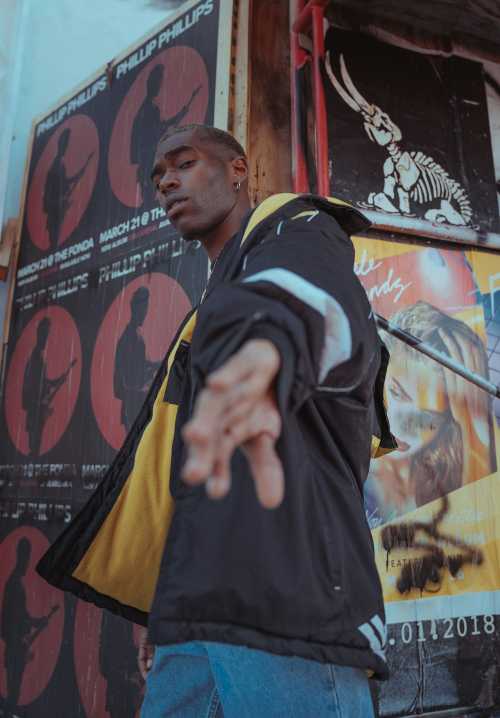
The Speculative Asset Trap
Managing a streetwear brand in 2026 resembles operating a high-frequency trading desk where the underlying assets are cotton hoodies, and market volatility is dictated by algorithmic resale bots rather than consumer utility. The defining shock of the current streetwear landscape is the simultaneous convergence of aggressive secondary market dominance—where platforms like StockX and GOAT command tens of millions of monthly visits—and a severe "post-luxury" consumer fatigue that has decoupled brand identity from mere inventory accumulation [[9]]. Concurrently, the European Union’s circular economy regulations are actively dismantling the opaque supply chains that traditionally fueled rapid-fire "drop" culture, forcing a structural reckoning across the entire sector [[28]].
The Liquidity Mirage of the Secondary Market
Mainstream financial coverage frequently celebrates the explosive growth of the authenticated resale segment as a testament to streetwear's enduring cultural capital and robust secondary market demand. In reality, this secondary market dominance represents a profound misallocation of brand equity and a dangerous surrender of pricing power. When resale platforms eclipse primary retail channels in both valuation and consumer engagement, the original brand cedes absolute control over its pricing architecture, customer data, and narrative. This dynamic fundamentally transforms streetwear from a wearable cultural expression into a purely speculative financial instrument, akin to unregulated derivatives. The capital that should be reinvested into community-building, design innovation, and immersive retail experiences is instead siphoned off by third-party marketplaces. These platforms monetize artificial scarcity and hype cycles without bearing the immense operational, logistical, and creative costs of actual brand stewardship or garment production.
Counter-Argument: The Resale Ecosystem as Brand Amplifier
Proponents of the resale ecosystem correctly argue that platforms like StockX and GOAT provide essential liquidity and authentication services that protect consumers from counterfeits, thereby expanding the total addressable market for heritage streetwear labels. They contend that high resale values serve as a powerful marketing engine, elevating brand prestige and driving frenzied demand for primary releases. However, this perspective dangerously ignores the long-term erosion of brand loyalty. When a consumer's primary relationship is with a resale platform rather than the brand itself, the label becomes commoditized. The brand is reduced to a mere ticker symbol in a speculative market, vulnerable to sudden shifts in algorithmic trends and macroeconomic liquidity, rather than being anchored by genuine, enduring consumer affinity.
The Regulatory Chokehold on "Hype" Manufacturing
Simultaneously, the sustainable streetwear market is being fundamentally reshaped by tightening trade regulations, particularly the EU's circular economy action plan, which demands rigorous proof of material integrity, manufacturing ethics, and end-of-life product management [[28]]. For decades, the streetwear industry thrived on a highly optimized model of rapid iteration, limited-run "drops," and opaque, outsourced manufacturing in jurisdictions with lax environmental oversight. The new regulatory framework, including impending Digital Product Passport (DPP) mandates, requires comprehensive supply chain transparency and strict recycled content quotas. This is not a superficial branding exercise or a simple swap of conventional cotton for organic alternatives; it is a capital-intensive operational overhaul. Independent labels that previously relied on rapid, low-cost production cycles to fuel hype culture now face existential margin compression. Compliance costs will disproportionately favor well-capitalized legacy conglomerates that can absorb the regulatory burden, effectively sterilizing grassroots innovation and raising the barrier to entry for emerging designers.
Echoes of the 2018 Hypebeast Peak
This current market correction mirrors the chaotic aftermath of the 2018 "hypebeast" peak, a period when luxury conglomerates aggressively acquired or partnered with streetwear labels, flooding the market with logo-centric collaborations and artificial scarcity. At that time, venture capital and private equity poured into the sector based on the flawed assumption that "hype" was a perpetual, scalable growth metric independent of macroeconomic conditions. When the market became saturated, and the novelty of the serialized "drop" model faded, valuations collapsed spectacularly. Many overextended, hype-dependent brands were left as distressed assets, acquired for pennies on the dollar by larger entities seeking to strip-mine their remaining cultural relevance. The historical lesson is unequivocal: when an industry expands on the basis of speculative fervor and manufactured exclusivity rather than enduring product utility and genuine community connection, the subsequent correction is both swift and punitive. We are witnessing the exact same structural vulnerability today, with resale speculation merely replacing primary market hype as the unstable foundation.
The Post-Luxury Identity Crisis
Furthermore, the broader streetwear sector is navigating a severe "post-luxury" identity crisis. As industry analysts have sharply observed, "Identity became inventory. Consumers didn't abandon streetwear. They simply stopped believing in it" [[21]]. The democratization of high-quality manufacturing and the concurrent rise of hyper-local, community-driven brands like Corteiz and Represent—which continue to see sell-out success by prioritizing authentic cultural resonance and regional identity over global, homogenized scale—have exposed the hollow core of mass-market streetwear [[19]]. Legacy brands that rely on recycled archival designs, inflated price points, and celebrity endorsements are finding that the modern consumer is increasingly adept at distinguishing between genuine cultural contribution and extractive, algorithmic marketing. The cultural cachet that once justified a 1,000% markup on a basic cotton hoodie has evaporated, replaced by a demand for tangible value and authentic brand ethos.
Counter-Argument: The Sustainability Premium Fallacy
Defenders of the traditional high-margin streetwear model frequently counter that premium pricing is necessary to fund the high-cost collaborations and experiential retail environments that define the genre. They argue that the "sustainability premium" demanded by new regulations will price out the core demographic that originally built the culture, effectively gentrifying streetwear and stripping it of its accessible, subcultural roots. Yet, this argument relies on a flawed understanding of modern consumer behavior. Today's streetwear consumer is increasingly values-driven; they are willing to pay a premium for verifiable sustainability and ethical production, viewing it as a marker of quality and brand integrity rather than an exclusionary tax.
Strategic Imperatives for Market Participants
Local streetwear retailers, independent designers, and community stakeholders must immediately pivot from growth-at-all-costs to structural resilience.
Internalize the Secondary Market: Brands must aggressively develop proprietary, authenticated resale or trade-in programs, thereby recapturing the margin and customer data currently surrendered to third-party platforms.
Pre-empt Supply Chain Shocks: Independent labels should prioritize supply chain transparency and secure certifications for sustainable materials now, locking in compliant manufacturing partners before the 2026 regulatory deadlines trigger industry-wide bottlenecks.
Pivot to Staple Resilience: Retailers must shift their inventory strategies away from speculative, hype-driven collaborations and toward timeless, high-quality staple pieces that offer consistent sell-through rates and protect against the volatility of trend cycles.
The Six-Month Horizon
Within the next six months, the streetwear landscape will experience a violent, structural consolidation. We will see at least two major legacy fashion conglomerates announce the acquisition of hyper-local, community-driven streetwear brands specifically for their authentic cultural capital and compliant supply chains, while quietly discarding the acquired brand's original, unsustainable operational models. Concurrently, the Federal Trade Commission or equivalent European regulatory bodies will initiate their first major enforcement actions against streetwear brands for unsubstantiated sustainability claims or manipulative "drop" mechanics, establishing strict, precedent-setting boundaries for digital retail. The era of the speculative hype cycle is over; the next phase belongs exclusively to brands that can seamlessly marry cultural authenticity with operational and regulatory fortitude.
Related Articles
The Hype Correction: How Algorithmic Flippers and Gorpcore Gluts Are Forcing a Streetwear Market Reset
Sep 16, 2026
The Algorithmic Enclosure: How Regulatory Squeezes and Clinical Consolidation are Rewiring the Beauty Paradigm
Sep 15, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account