
Football's Quiet Leveraged Buyout Boom Is Being Underwritten by Your Local Pub

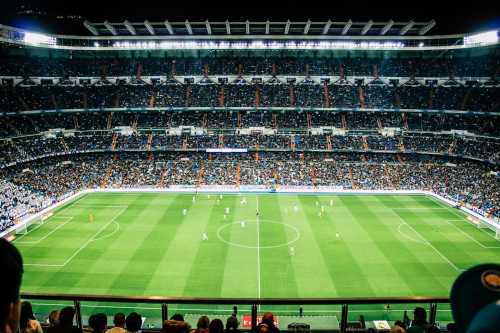
Buy a chain of twelve restaurants using the restaurants' own future takings as collateral and you have not acquired a business. You have borrowed one. European football has spent the last three years running precisely that trade, dressing it in scarves and calling it ambition. Private-equity consortia and multi-club networks have accelerated debt-financed acquisitions of European clubs at the exact moment UEFA's Financial Sustainability Regulations tighten the squad cost ratio to 70 per cent of revenue from the 2025/26 season, compressing the very cash flows those acquisitions were underwritten against.
The Balance Sheet Is Now the Team Sheet
Mainstand coverage treated the ownership churn as a glamour story — new money, new stadium renders, new silverware timelines. The mechanism is more prosaic and more dangerous. Acquisition debt is serviced from revenue that is sold forward on multi-year broadcasting and sponsorship contracts. When the ratio binding a club's wage bill tightens, the equity cushion evaporates first, because wages are the only large cost a club can actually cut, and cutting them degrades the asset that justifies the purchase price. Owners are therefore trapped in a pro forma loop: borrow to buy, spend to win, sell the winning to refinance the borrowing.
The Rule Designed to Protect Clubs Is Concentrating Them
Here is what the sports desk is not printing. A spending cap expressed as a percentage of revenue is not neutral. It is a direct transfer of competitive advantage to clubs whose income does not come from football. According to Deloitte's Football Money League, Premier League aggregate revenue has pushed beyond the €6 billion mark, with commercial income at several leading clubs now rivaling broadcast receipts — revenue streams built on global retail, real estate and media partnerships that a mid-table club with one stadium and one city cannot replicate. A 70 per cent ceiling is comfortably absorbable at €600 million of revenue and suffocating at €90 million. The regulation therefore does not restrain spending. It ratifies who is already rich, converting financial governance into a structural barrier to entry and accelerating the concentration it was drafted to prevent.
Your High Street Is the Collateral
The second blind spot is geographic. When a leveraged club needs liquidity, the first assets monetised are not players. They are naming rights, hospitality suites, catering concessions, retail licences and, increasingly, sale-leaseback of the ground itself. Every one of those contracts is staffed locally: the caterer, the printer, the security firm, the coach operator, the matchday trader. A refinancing negotiated in Luxembourg becomes a payroll event in a post-industrial city within two quarters, and it arrives as vendor-term extension rather than as redundancy, which is why nobody counts it. Supporters are asked to defend a badge while the revenue that employs their neighbours is being securitised and assigned to a lender. The stadium stops being a venue and becomes an encumbrance.
The World Cup Nobody Costed
Third, and least discussed: the expanded 48-team summer tournament absorbed the pre-season window, inflated fixture congestion and pushed medical and squad-rotation costs into a season that is now shorter in revenue-generating terms. Coverage framed it as a sporting calendar inconvenience. It is a working-capital event. Clubs carrying acquisition debt entered the campaign with compressed commercial activation periods, fatigued assets and higher insurance and rehabilitation costs, precisely as the spending ratio tightened. That is a three-way squeeze on the same line item.
The Case For Leverage, Stated Fairly
Intellectual honesty requires the opposite brief. Private equity has, in several documented cases, installed audited reporting, board discipline and capital expenditure that sentimental family ownership deferred for a decade — academies rebuilt, training grounds financed, debt refinanced at lower coupons than the owner's informal loans. The pre-leverage status quo was not more sustainable; it was less transparent, financed by petrostate transfers and lottery-scale personal fortunes that vanished with the principal. Blaming structure rather than supervision is the easy error, and the sector's genuinely reckless era was the one with no lender at the table asking questions.
The ITV Digital Precedent Nobody Booked
Football has run this experiment before. When ITV Digital collapsed in 2001, roughly £170 million of committed broadcast income disappeared overnight and clubs that had borrowed against it — Bradford City among them — went into administration within months. The lesson was never that debt is immoral. It was tenor mismatch: fixed obligations written against floating, contract-dependent revenue. Clubs repeat the mistake every cycle because revenue is sold forward at optimistic valuations and debt is booked at face value, and the gap between those two numbers is the entire risk. Regulators have improved the ratio. They have not improved the maturity profile, which is where clubs actually die.
What To Do Before The Next Refinancing
- Matchday suppliers: invoice weekly, not monthly, during any announced refinancing; insist on parent or personal guarantees and 24-month terms. Your receivable is junior to the lender's charge and you will learn that last.
- Supporters' trusts: pursue asset-holding vehicles and golden-share arrangements for the ground itself. If the stadium can be sold in a restructuring, the club cannot survive one.
- Investors and informed fans: read the related-party management fee and the sale-leaseback announcement, not the league table. Both precede distress by two to three quarters and are filed where nobody looks.
- Boards: term acquisition debt into revenue-linked instruments before the next domestic rights cycle, not after it. Refinancing into a bidding war is solvable; refinancing out of one is not.
Six Months Out
Expect the first high-profile restructuring among debt-financed European clubs, and expect it to be explained as a sporting failure rather than a maturity problem. Expect ownership to split formally into an offshore brand vehicle and a local operating company, a structure that protects the mark and abandons the payroll. Expect wage deflation and a seller's market in the transfer window as clubs liquidate the only unencumbered asset they own. And expect points deductions to become routine enforcement rather than scandal, because a ratio enforced by sanction is a tax, and clubs will price it as one. The badge will be fine. The company behind it is the thing at risk, and it is the company that pays the caterer.
Related Articles
The Hype Cartel: How Cryptographic Scarcity and Secondary Royalties are Dismantling the Autonomous Streetwear Economy
Oct 19, 2026
The Enclosure of the Pitch: How Biometric Depreciation and Private Equity Arbitrage Are Fracturing Global Football
Oct 19, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account