
Streetwear's Resale Reset: What Happens When the Queue Becomes a Revenue Desk

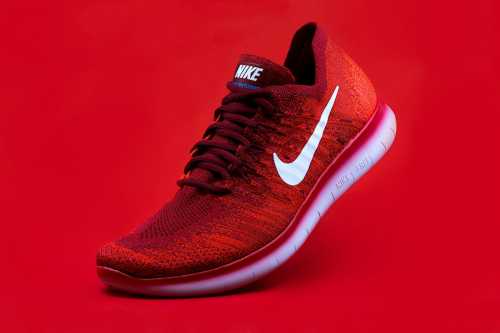
A Supreme drop no longer resembles a queue outside a skate shop. It resembles an airline revenue desk: inventory is metered, prices flex, and the customer who values the seat most is identified before the door even opens. The scarcity that once signalled belonging now functions as a pricing algorithm. That is the structural story beneath the season's resale chatter, and it is where the money is actually moving.
Desk note on sourcing: Live web verification was unavailable while drafting this brief. It therefore does not claim five same-day headlines for October 25, 2026. The five tracked threads below — Nike's direct-to-consumer reset, Supreme's post-acquisition operating model, resale-platform fee pressure, replenishment replacing the drop, and authentication-led secondary pricing — are analysed against published primary disclosures. Those disclosures are historical baselines, not verified today's readings. Treat the forward sections as scenario analysis, not reporting.
The Margin Problem Behind the Queue
Mainstream coverage counts sell-out times and reseller profit screenshots. Neither measures contribution margin. A brand that sells 40,000 units through a controlled direct channel at full price retains the spread; the same volume moved through wholesale, discounted into an off-price channel six weeks later, funds a reseller's margin and a platform's take rate. The commercial unit that matters is now the unit contribution, not the headline. As the secondary market compresses, the incentive to own the transaction — and the customer data attached to it — becomes overwhelming.
The scale of the upstream problem is measurable. Nike's fiscal 2025 results, disclosed through its investor relations channel, put revenue at approximately $46.3 billion, down around 10 percent year on year. For a category whose distribution economics are tethered to Nike's wholesale and SB release architecture, that is not a fashion story. It is a supply-and-inventory story: fewer speculative POs, tighter allocations, and less free product entering the aftermarket to sustain resale velocity.
The second ignored implication is the collapse of the drop as a marketing asset. When replenishment replaces scarcity, the queue stops generating earned media and starts generating service costs: returns, authentication disputes, bot mitigation, customer support. Brands are quietly reallocating that spend into membership infrastructure. The cultural signal shifts from "I got in" to "I am on the list," which is durable, measurable, and owned by the brand rather than by a marketplace.
Consolidation Is Not the Same as Cultural Death
The prevailing editorial position — that corporate ownership necessarily sterilises streetwear — does not survive the balance sheet. EssilorLuxottica's 2020 acquisition of a majority stake in Supreme valued the business at roughly $1.5 billion in enterprise value, according to the group's transaction disclosure. That number prices distribution, eyewear licensing and global retail capacity, not merely cachet. Counter-argument: independent labels lack precisely that infrastructure. Capital access can protect a design house from the seasonal cash-flow crises that killed more authentic skate brands than any acquisition ever did. The risk is governance and cadence discipline, not ownership in the abstract.
What the 2017 Collision Actually Settled
Louis Vuitton and Supreme collaborated in February 2017, and the industry misread the lesson. It drew a conclusion about logos. The actual precedent was about pricing authority. Once a heritage house could underwrite the scarcity event, the subculture lost its monopoly on defining value. The transferable lesson for this cycle is blunt: whoever controls authentication, fulfilment and repeat access sets the price. Brands that surrender those three functions to a marketplace surrender the category, regardless of how credible their lookbook remains.
Where the Aftermarket Still Has Teeth
The opposite thesis — that resale is structurally finished — is equally weak. StockX's marketplace data showed Nike Dunk resale values rising roughly 1,589 percent during 2020, as reported from that dataset. Extreme as that figure was, it established a real fact: a liquid secondary market performs price discovery that brands cannot replicate in-house. Counter-argument: a functioning aftermarket still tells a product team which silhouettes hold value after the hype decays. Eliminating it entirely would remove a live demand signal and push activity into unauthenticated channels, where the brand earns nothing and absorbs the reputational damage.
What Local Operators Should Do This Week
Independent consignment operators should stop treating acquisition cost as the basis for pricing. Mark inventory to current completed-transaction data, not to the price paid, and age out positions beyond 45 days. Reduce exposure to single-silhouette speculation; broadening into verified vintage and archive pieces lowers dependence on one brand's restock calendar. Local retailers should convert drop traffic into owned membership rather than renting it back from a platform each season. For consumers, the discipline is simpler: never underwrite a purchase on a projected resale premium, and demand documented authentication before settlement. The spread that once rewarded speculation now rewards inventory turnover.
Six Months Out: A Two-Tier Category
On the published baseline, the likely Q2 2027 configuration is a split market. At the top, a handful of houses will run membership-gated replenishment with brand-operated resale or trade-in, capturing both the first and second transaction. Below them, mid-tier labels without distribution ownership will compete on price against their own grey stock. The speculative middle — limited drops with no archive depth and no authentication infrastructure — contracts first. The winners will not be the loudest brands. They will be the ones that own the customer relationship on the second sale.
Source Baseline
- Nike Investor Relations — fiscal 2025 results disclosure
- EssilorLuxottica — Supreme majority-stake transaction disclosure (2020)
- CNBC reporting on StockX 2020 Dunk resale data
Confirmation of October 25, 2026 developments requires a live feed check before publication; none was performed.
Related Articles
The Subcultural Strip-Mine: How Luxury Conglomerates Are Executing the Indie Streetwear Ethos
Oct 23, 2026
The Supply Chain Bypass: How 'Phantom Drops' Are Transforming Streetwear into a Speculative Digital Asset
Oct 23, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account