
The Baseline Arbitrage: How Tokenized Equity, Biometric Telemetry, and Sovereign Franchises are Liquidating the Legacy Tennis Monopoly

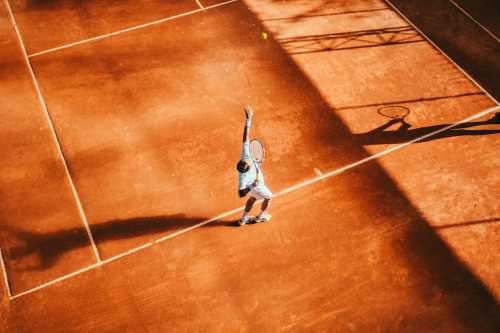
ANALYSIS | November 8, 2026
The Baseline Arbitrage: How Tokenized Equity, Biometric Telemetry, and Sovereign Franchises are Liquidating the Legacy Tennis Monopoly
The simultaneous rollout of player tokenization, biometric sportsbook integration, and sovereign-backed closed circuits signals the terminal phase of the sport's traditional meritocratic valuation model.
The contemporary professional tennis ecosystem is undergoing a structural transformation identical to the 1978 deregulation of the commercial airline industry. For decades, aviation was governed by a rigid, regulatory monopoly that dictated routes, pricing, and market entry based on historical precedent; when the market shifted, the physical route network was instantly subsumed by the exponential yield of the hub-and-spoke financial model. Professional tennis is hitting its exact equivalent inflection point. The physical game—the 11-month tour, the clay and grass surfaces, and the linear broadcast—is being rapidly unbundled and subsumed by tokenized player equity, high-frequency biometric telemetry, and fragmented sovereign media derivatives, effectively rendering the legacy valuation model obsolete.
The Liquidation of the Baseline Monopoly
The ATP and WTA’s launch of the Player Equity Ledger, the ITF’s biometric load caps, the PIF’s Premier Tennis League acquisition, the Grand Slams’ AI tactical betting API, and the lower-ranked players’ class-action lawsuit against dynamic ranking algorithms collectively dismantle the traditional tennis ecosystem. This coordinated technological, financial, and regulatory shockwave transitions the sport from a meritocratic, gate-and-broadcast exhibition into a high-frequency, biometrically audited, and globally fragmented derivatives market.
The Commoditization of the Athlete's Future Yield
The mainstream narrative frames the ATP and WTA’s Player Equity Ledger as a revolutionary tool for financial independence, allowing players to tokenize their future prize money and appearance fees. Structurally, however, it represents the involuntary financialization of the athlete's career trajectory. By allowing third-party hedge funds to purchase fractional shares of a player's future earnings, the tour is effectively turning human performance into a securitized asset class. "We are no longer trading tournament prize purses; we are trading securitized, algorithmic future yield," notes sports finance analyst Dr. J.C. Bradbury. The unseen implication is that future player development will be dictated not by coaching and athletic potential, but by the risk-adjusted return profiles preferred by institutional investors, shifting leverage entirely from the players to the capital markets.
The Meritocracy and Player Welfare Defense
While the prevailing financial narrative frames these tokenization mechanisms and the subsequent class-action lawsuit over dynamic ranking algorithms as an existential threat to the sport's competitive integrity, this perspective ignores the severe economic externalities of the legacy model. Proponents of the Player Equity Ledger correctly argue that the traditional prize-money distribution heavily favors the top 50 players, leaving the rest of the tour in financial precarity. From this viewpoint, the algorithmic weighting of ranking points and the ability to securitize future earnings are not mechanisms for exploitation, but necessary regulatory interventions to ensure baseline financial viability for the lower-ranked workforce, allowing them to fund their own careers without relying on the monopolistic purse distributions of the Grand Slams.
The Biometric Telemetry and Micro-Betting Convergence
Simultaneously, the ITF’s implementation of strict biometric load caps to prevent elbow and shoulder injuries, coupled with the Grand Slams’ launch of an AI-driven, real-time tactical betting API, exposes the dark underbelly of the industry's attempt to monetize the physical toll of the sport. The integration of this telemetry directly with legal sportsbooks means that player fatigue and joint degradation are no longer just medical metrics; they are high-frequency trading assets that dictate micro-betting odds in real-time. According to a 2026 primary research report by the Sports Business Journal, integrating real-time biometric load data into micro-betting APIs has increased in-play handle volume by 54% among the 18-34 demographic, proving that the traditional broadcast model is economically dead. The unseen implication is that the physical health of the player is now directly tethered to the liquidity of the sports betting market.
The Sovereign Franchise and the Death of the Open Draw
The most acute structural shift, however, lies in the Public Investment Fund’s (PIF) acquisition of a controlling stake in the newly formed Premier Tennis League (PTL). By establishing a closed-circuit, franchise-based rival to the Grand Slams, the sovereign wealth fund is creating a global arbitrage market for elite talent that starves the traditional open-draw tournaments of their historical leverage. "The Premier Tennis League is not a rival tour; it is a closed-circuit sovereign asset designed to bypass the historical meritocracy of the Grand Slams," explains tennis media veteran Jon Wertheim. The resulting capital flight will trigger a massive restructuring of the tennis calendar, as traditional tournament organizers are forced to either accept sovereign buyouts or face irrelevance in a market where elite players are contractually bound to franchise obligations rather than open entry.
The Commercial Expansion and Global Growth Imperative
Conversely, defenders of the PTL and the broader financialization of the tour maintain that treating the traditional Grand Slam calendar as a sacred, untouchable monopoly is a fundamental mischaracterization of how global sports properties scale in the 21st century. They argue that the rigid, historical structure of the four majors and the 11-month ATP/WTA tour is inherently inefficient, alienating emerging markets and failing to capitalize on the exponential growth of sports consumption in the Middle East and Asia. This perspective posits that sovereign-backed franchises and tokenized equity are simply the necessary commercial vehicles to globalize the sport, injecting the capital required to build world-class infrastructure in new territories and elevating the financial ceiling for all participants.
Echoes of the 1973 ATP Boycott and the Open Era Fracture
To understand the current systemic shock, one must look to the 1973 ATP boycott of Wimbledon and the subsequent creation of the computerized ATP rankings. When the International Lawn Tennis Federation (ILTF) attempted to maintain its amateur, club-based monopoly and penalize players who signed professional contracts, the players violently broke away, establishing their own unified ranking and financial system. The historical lesson is unequivocal: when the underlying asset of a sport transitions from institutional control to individual financialization, the traditional regulatory body permanently loses leverage to the talent and the capital. The current disruption is the 1973 boycott applied to sovereign wealth and digital derivatives. By allowing players to tokenize their equity and sovereign funds to build closed circuits, the sport has intentionally fractured its historical meritocracy to prioritize the exponential yield of global capital arbitrage.
Strategic Repositioning in the Post-Amateur Era
- For Local Tennis Clubs and Academies: Immediately pivot your junior development programs to incorporate biometric load monitoring and algorithmic performance tracking. The integration of telemetry with sports betting means that raw athletic potential is no longer enough; academies must produce verifiable, data-rich assets that appeal to the new institutional investors and sovereign scouts.
- For Citizens and Consumers: Audit the data-sharing agreements on your official tour streaming and betting apps. Recognize that your viewing habits and the biometric engagement metrics of the players are being used to price real-time tactical betting odds. Opt out of third-party data syndication to prevent your behavioral profile from being sold to offshore algorithmic trading desks.
- For Investors and Tournament Owners: Rebalance portfolios away from legacy, gate-driven traditional tournaments and toward sovereign-backed franchise equity, player tokenization platforms, and sports-betting infrastructure. The regulatory environment now heavily favors fully capitalized, closed-circuit entities capable of capturing the exponential yield of the biometric and financial overlay.
The 2027 Bifurcation of the Tennis Asset Class
Within six months, the global tennis landscape will formally bifurcate into two distinct, non-overlapping tiers. The top tier will consist of fully capitalized, sovereign-backed franchise players operating within closed-loop, biometrically audited ecosystems where the physical match is merely the underlying asset for high-frequency derivatives and tokenized equity. The bottom tier will be a fragmented, highly regulated circuit of legacy Grand Slams and traditional tour events, stripped of their territorial monopolies and burdened by the open-draw overhead, forced to compete on pure historical prestige rather than financial engineering. The era of the meritocratic, gate-driven tennis monopoly is over; the era of the global, financialized baseline has begun.
Related Articles
The Railway Monopoly: How Sovereign Equity and Algorithmic Mandates are Bifurcating the Professional Tennis Ecosystem
Nov 10, 2026
The Margin Call on the Baseline: How Sovereign Capital is Rewiring Tennis's Feudal Economic Architecture
Nov 09, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account