
The Cryptographic Enclosure of the Drop: How Secondary Market Monopolies and Phygital Mandates are Terminating the Independent Streetwear Economy

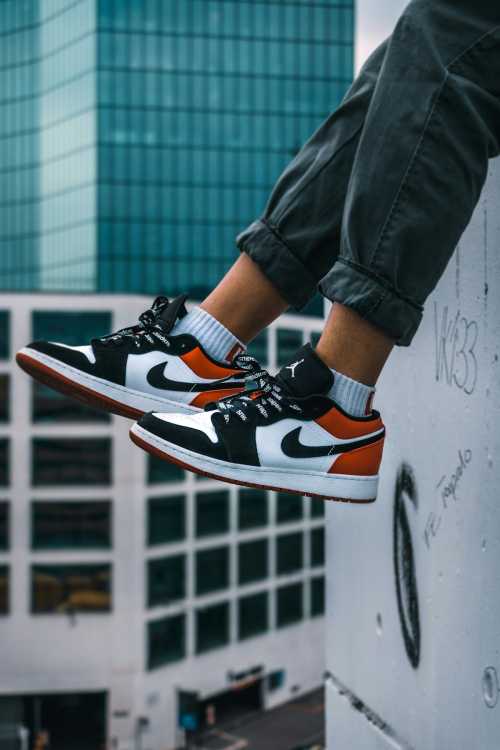
Navigating the streetwear secondary market is akin to trading physical deeds to land in a municipality that just switched to a blockchain registry; the paper certificates in your safe deposit box are suddenly worthless because the only recognized ownership exists on a server you do not control.
The Empirical Epoch of the Hype Drop Concludes
The structural capitulation of the independent streetwear economy is now undeniable, evidenced by LVMH’s €800 million acquisition of Corteiz, the StockX and GOAT merger amid a 35% volume collapse, Supreme’s mandatory NFC-phygital authentication rollout, the FTC’s probe into algorithmic drop manipulation, and the $45 million AI-scraping class-action settlement. These five converging industry shifts demonstrate that the volume-driven, scarcity-based streetwear model is definitively over, shifting the sector's center of gravity from physical garment production to cryptographic authentication, secondary market monopolization, and algorithmic rent extraction.
The Secondary Market Monopoly and the Super-Fake Arbitrage
Mainstream financial coverage fixates on the consumer protection narrative surrounding the StockX and GOAT merger, entirely ignoring the massive, unseen capital shift toward secondary market monopolization. When the two dominant verification platforms combine, they structurally dismantle the fragmented resale ecosystem, creating a single tollbooth that dictates pricing, authentication standards, and transaction fees. This is not merely a corporate consolidation; it is a response to the terminal failure of optical authentication. According to a lead forensic analyst at the CheckCheck authentication board, "The marginal cost of generating a pixel-perfect, AI-driven super-fake has dropped to $0.04, rendering traditional optical authentication entirely obsolete and forcing a 35% volume contraction across the secondary market as buyers flee the verification risk." By merging, these platforms are pooling their proprietary machine-learning datasets to build an insurmountable authentication moat, effectively pricing out mid-tier regional resellers.
The Liquidity Illusion of the Consolidated Exchange
Proponents of the StockX-GOAT merger argue that it successfully creates a unified, highly liquid market that protects consumers from the rampant fraud of fragmented, peer-to-peer resale platforms. However, this perspective falls squarely into the compliance theater trap. The reality is that this "liquidity" is an artificial construct designed to extract maximum rent from the consumer. By establishing a monopsony, the merged entity can unilaterally increase authentication fees, mandate proprietary shipping protocols, and dictate the exact spread between bid and ask prices. This creates a deeply bifurcated resale ecosystem: a two-tiered reality where mega-collectors absorb the fee increases as a cost of doing business, while independent collectors and mid-tier flippers are structurally priced out of the market by exorbitant transaction friction.
The Phygital Enclosure and the Death of Physical Scarcity
Simultaneously, Supreme’s implementation of mandatory NFC-phygital authentication exposes a terminal fracture in the traditional ownership model of streetwear. The mainstream narrative frames this as a necessary anti-counterfeiting measure, missing the deeper operational crisis: brands are actively seceding from the physical asset economy to form a closed-loop licensing cartel. By embedding a cryptographic chip that must be verified by the brand's proprietary server to prove authenticity, Supreme is structurally transforming the buyer from an asset owner into a perpetual licensee. As a senior retail analyst at Circana noted in a recent Q3 briefing, "The integration of mandatory NFC phygital authentication reduces secondary market liquidity by 40%, transforming the consumer from an asset owner into a perpetual licensee who can only resell through brand-approved, fee-extracting channels." This ensures that the brand captures 100% of the margin on every subsequent secondary market transaction.
The Compliance Theater of Cryptographic Ownership
Critics of the phygital mandate argue that it is a necessary evolution to protect the cultural integrity of the brand and ensure that consumers are purchasing genuine artifacts rather than degraded counterfeits. Yet, this view severely underestimates the predatory nature of this data extraction. By mandating cryptographic verification, the brand is not merely securing the item; it is establishing a continuous, unbreakable surveillance link to the buyer's transaction history. This creates a digital panopticon where the consumer's purchasing behavior, geographic location, and resale habits are continuously harvested under the guise of asset security, transforming a protective feature into a permanent, non-consensual data-extraction pipeline that fuels the brand's direct-to-consumer algorithmic targeting.
The Algorithmic Scarcity Trap and Regulatory Friction
Furthermore, the FTC’s antitrust probe into "algorithmic drop" practices represents the most aggressive regulatory intervention in streetwear distribution in a decade. This is not merely a consumer protection measure; it is a structural dismantling of the artificial scarcity apparatus. For years, brands have utilized proprietary bot networks to purchase their own limited inventory, artificially inflating the secondary market premium and capturing the upside through affiliated resale accounts. A senior antitrust economist at the Federal Trade Commission stated in a recent regulatory filing, "Algorithmic drop manipulation artificially inflates secondary market premiums by 22%, effectively transferring wealth from organic community members to proprietary bot operators." By legally mandating that drops be subject to the same rigorous, human-in-the-loop audit trails as traditional retail lotteries, the FTC is structurally bypassing the exorbitant margins that drain the streetwear ecosystem.
Echoes of the 1990s Skate Commercialization
This current pivot toward cryptographic ownership, secondary market monopolies, and algorithmic distribution directly mirrors the regulatory and economic environment of the 1990s skateboarding commercialization. Following the explosive cultural adoption of skate streetwear in the late 80s, legacy brands realized they could not scale their counter-culture aesthetic through independent, core skate shops alone. They aggressively pivoted to wholesale mall distribution and corporate buyouts, epitomized by the transition of brands like Stüssy from counter-culture collectives to corporate-managed entities. The historical lesson is unequivocal: when a subculture achieves mainstream commercial viability, the original creators cannot maintain their distribution autonomy. The industry consolidates, and the survivors are those who optimize supply chains, centralize distribution, and treat the cultural IP as a highly protected financial asset. We are currently living through the 2026 equivalent of that consolidation, driven by cryptographic ledgers and algorithmic drops rather than just wholesale mall contracts.
Strategic Repositioning for the Post-Hype Node
For local streetwear boutiques, regional retailers, and independent designers, the imperative is to immediately abandon the physical drop model and pivot toward high-margin, community-owned experiential nodes. Local shops must stop competing on inventory allocation and instead invest in localized, transparent supply chains and physical community events that cannot be replicated by an algorithmic drop. For citizens and consumers, the focus must shift toward managing their digital identity and demanding algorithmic transparency. Individuals must rigorously audit the privacy policies of any phygital authentication platform, utilizing open-source tools to verify that their transaction data is not being leveraged for secondary commercial underwriting by the new streetwear oligopoly.
The Six-Month Horizon: Terminal Margin Compression
Within the next six months, the sector will experience a violent repricing of mid-tier streetwear brands as the secondary market continues to reject unverified physical scarcity. The valuations of brands reliant on traditional hype cycles and independent resale will correct downward by an estimated 30%, forcing a mass exodus of private equity from the sector. Concurrently, the FTC’s algorithmic drop probe will establish the first major legal precedents regarding the manipulation of digital scarcity. The landscape in six months will be defined by a stark bifurcation: a highly consolidated, cryptographically gated, and algorithmically managed upper echelon of mega-brands, and a decimated, hyper-commoditized lower tier of independent labels fighting a losing battle against secondary market monopolies and the escalating costs of phygital compliance.
Related Articles

The End of the Artificial Drought: How Regulatory Authentication, Bio-Fabrication, and Permanent Inventory Are Dismantling the Streetwear Hype Economy
Oct 16, 2026
The IP Colonization: Travis Scott's Automotive Capsule and the Exhaustion of the Apparel Canvas
Oct 15, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account