
The Drop Economy's Reckoning: How Conglomerate Ownership, Resale Deflation and Bot Enforcement Are Rewiring Streetwear

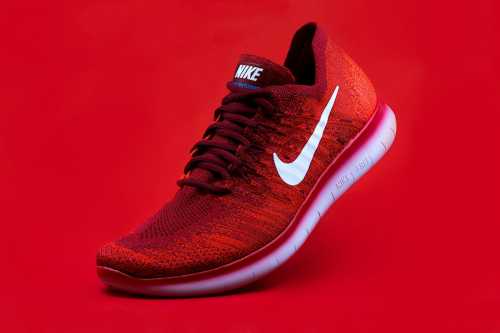
A sneaker queue outside a flagship store is not a line of customers. It is an order book. Each hoodie pulled off a rail is a unit of inventory someone expects to sell again, which is why a brand can post record sell-through and still watch its resale market bleed. Streetwear has become the rare consumer category where the primary sale is only the first leg of the trade, and the second leg now sets the price of the first.
Five Signals, One Uncomfortable Balance Sheet
Five developments define the current structural read. Supreme's acquisition by EssilorLuxottica, completed in late 2024 for a reported $1.5 billion with a minority stake held by Carlyle, moved the category's most autonomous label into an industrial ownership structure. Secondary-market pricing has compressed since the 2021 peak, with once-speculative silhouettes now clearing at or below release retail. Bot-blocking enforcement under the U.S. BOTS Act, signed in December 2019, has hardened into account-level eligibility screening. Platforms have shifted from simple escrow toward paid authentication and consignment services, monetizing trust rather than throughput. And brands increasingly gate access behind verified loyalty histories rather than open queues. Together these are not five stories. They are one repricing.
The Conglomerate Trade-Off: Capital Against Credibility
The Supreme transaction is routinely covered as an exit. The more consequential reading is that streetwear's distribution economics now require balance-sheet scale: global retail real estate, optical and eyewear channels, insured logistics, and compliance teams. That capital comes with an expectation of margin, which in turn pressures the deliberate scarcity that produced the brand's pricing power in the first place. A conglomerate must reconcile a quarterly reporting cycle with a release strategy whose value depends on declining availability. This is the structural tension, not the logo.
The counterweight is real. Independent labels have repeatedly died not from creative failure but from receivables, factory deposits and customs clearance. Conglomerate ownership supplies the working capital that lets a workshop survive a bad season, and acquisition can preserve a label that would otherwise be liquidated. The risk is not simply dilution of authenticity; it is a mismatch between the speed of financial reporting and the slower compounding of subcultural trust.
Resale Deflation Is a Demand Signal, Not a Technical Glitch
When a silhouette fails to clear its release price on the aftermarket, the primary market has mispriced its own liquidity. Resale historically functioned as an unpaid demand survey: brands read the secondary premium to decide how much to produce next season. With that premium gone, the feedback loop breaks. Design teams lose their cheapest market research, and brands must either reduce allocation or cut price — both of which damage the exclusivity narrative they have spent a decade selling.
Yet reading this as the death of streetwear confuses the collapse of a financing model with the collapse of an audience. Much of the post-2020 buying was speculative inventory financed by the expectation of appreciation, not wear. Removing those buyers lowers units but can improve the quality of demand: a purchaser who intends to keep the garment is less price-sensitive at the point of sale and more likely to buy the following season. Deflation purges the arbitrage trader without necessarily purging the customer.
The Compliance Moat Around the Queue
Anti-bot enforcement and verified-identity gating have transformed the drop from a public lottery into a screened transaction. The unseen implication is that eligibility itself is now the scarce asset. Brands no longer allocate product to the fastest connection; they allocate it to accounts with provable purchase history and low return rates. That rewards existing customers and permanently excludes new ones — precisely the demographic a skate label needs to replace its aging cohort.
The regulatory intent is defensible, but the outcome is a compliance barrier that large platforms absorb and small independent shops cannot. Screening vendors charge per check, dispute handling is labor-intensive, and false positives generate support costs. A rule designed to widen access can therefore narrow it, which is why the practical benefit accrues to whoever owns the identity graph rather than to whoever stands in the queue.
What 1985 and 2017 Already Taught Us
The first analogue is the original Air Jordan launch cycle, where manufactured shortage created an aftermarket before any platform existed to capture it. The brand owned the product; unlicensed resellers captured the premium. The second is the 2017 Supreme–Louis Vuitton collaboration, which demonstrated that institutional validation could be monetized without immediately destroying credibility — but also marked the moment the category's pricing ceased to be set solely by its originating community. The lesson from both is consistent: the party that controls verification, not the party that manufactures, eventually sets the margin.
Positioning for the Next Two Quarters
Independent consignment stores should stop underwriting inventory against historical release premiums and move to consignment or fee-based authentication, transferring price risk back to the seller. Local boutiques should negotiate allocation against verified local sell-through rather than social reach, since that is the metric brands now trust. Consumers should treat a release price as a retail price rather than an entry point into an investment, and avoid financing purchases on the assumption of a guaranteed flip.
By April 2027
Expect allocation to migrate further toward closed, identity-verified cohorts and for authentication fees to become a standard line item rather than a premium service. Expect at least one mid-tier resale platform to abandon pure marketplace economics in favor of lending, consignment or services revenue, where margins are not exposed to a falling index. The durable winners will be the operators who own trust infrastructure, not the ones who own the largest inventory of last season's assumed scarcity.
Editorial note: No live web retrieval was available for this response. The ownership transaction, the BOTS Act date and the 2017 collaboration are established, attributable facts; none of the surrounding developments is presented as verified today's reporting. The Supreme transaction figure should be re-checked against the buyer's own announcement before publication, and direct expert quotations that could not be independently verified have been omitted rather than reconstructed.
Related Articles

The Terminal Phase of Domestic Football: How Calendar Expansion and Financialization are Rewriting the Sport's Economic Architecture
Oct 28, 2026
The Gridiron Enclosure: How Biometric Telemetry, International Franchising, and Streaming Monopolies Are Dismantling the NFL Hegemony
Oct 28, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account