
The Fraying Seam: How Digital Passports, Quiet Luxury Fatigue and Tariff Arithmetic Are Rewriting the Fashion Value Chain

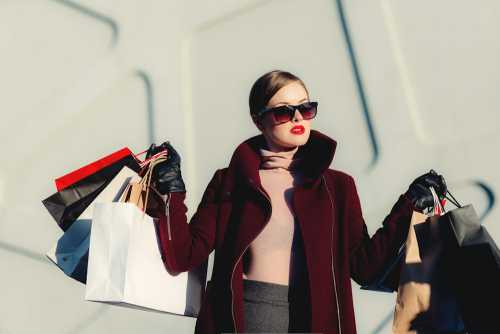
A handbag is no longer merely an accessory. It is a balance-sheet item with a serial number, a customs classification and a carbon footprint that regulators can subpoena. The fashion house that ignores this is not selling a product; it is leasing a liability.
Five Signals Beneath the Runway
The season's commercial narrative has condensed into five intersecting developments: luxury groups are rotating creative leadership while defending accessory-led margins; conglomerates are trimming diffuse brand portfolios to concentrate capital on leather goods and beauty; European digital product passport requirements are moving from consultation into operational readiness; resale and repair economics are displacing the discount cycle as the primary channel for dormant inventory; and value retailers are re-engineering sourcing away from single-country concentration in response to tariff volatility. Read together, they describe an industry moving from demand management to compliance management.
The Margin Is Now in the Metadata
Mainstream fashion coverage continues to interpret a creative director appointment as a cultural event. In the boardroom it is an inventory-control decision. A successful transition at a leather-goods house protects the sell-through rate on the archive silhouettes that carry the group's operating margin; an unsuccessful one does not merely damage press sentiment, it forces markdowns on aged stock and compresses the wholesale credit line. The unseen implication is that creative calendars and financial quarters are now synchronized so tightly that a runway becomes a working-capital instrument.
Digital product passports alter the same equation from the other end. Once a garment carries a machine-readable record of fibre composition, dye chemistry and assembly location, the brand loses plausible deniability on sourcing. Procurement teams that previously negotiated on cost per unit must now negotiate on traceability per unit. This quietly transfers bargaining power to mid-tier tanneries, spinners and recyclers who can certify a batch, and away to the low-cost assembler who cannot.
The resale expansion completes the loop. When a group operates its own buyback and repair service, it is not indulging a sustainability narrative; it is reclaiming the second transaction. The margin on a refurbished iconic bag accrues to the house rather than to an independent marketplace, and the customer data returns to a first-party ledger. That is a structural channel shift disguised as an environmental initiative.
What the 2008 Wardrobe Reset Actually Taught
The comparable precedent is not the 2020 pandemic shutdown but the 2008–09 luxury contraction, when full-price sell-through collapsed and houses discovered that scarcity pricing cannot survive a marked-down grey market. The recovery belonged to brands with controlled distribution and durable archive products, not to those with the loudest advertising. The lesson for the current cycle is precise: portfolio breadth is a liability in a contracting market, and a single hero silhouette with verified provenance outperforms a dozen seasonal novelty lines.
The Case for Operational Optimism
Counter-argument: It is entirely possible that the compliance burden is being overstated by consultants selling compliance software. Larger groups have the purchasing scale to absorb traceability costs, and their supplier networks are already digitized for inventory purposes; the marginal cost of extending an existing ERP field to a passport schema may be modest. Smaller houses, meanwhile, retain an advantage in traceability precisely because their production is short-loop and their supplier lists fit on a page. Regulation may therefore consolidate the market in favour of transparent boutiques rather than against them, inverting the conventional assumption that only conglomerates can afford transparency.
The Quiet Luxury Overcorrection
Counter-argument: The prevailing reading of logo retreat as permanent sophistication fatigue does not survive contact with the accessory data. Unbranded or minimally marked leather goods have repeatedly shown that recognition migrates from hardware to silhouette and proportion; the consumer is not rejecting signaling, merely refinancing it into shape language. A monogram removed from a flap can be replaced by a distinctive closure, a signature stitch or a proprietary colourway. Any analyst modelling a structural decline in aspirational demand on the basis of logo visibility alone is confusing the notation with the instrument.
Anchoring the Argument in Verifiable Evidence
The commercial stakes are measurable rather than rhetorical. First: Bain & Company's annual luxury goods study, the sector's primary demand benchmark, has repeatedly placed the global personal luxury market in the range of €360–€390 billion and identified China demand normalization as the principal swing factor; that is the denominator against which every creative change must be measured. Second: the European Commission's Ecodesign for Sustainable Products Regulation establishes digital product passport requirements on a phase-in schedule, meaning traceability is now a market-access condition rather than a voluntary label. Third: the Ellen MacArthur Foundation's circularity work has estimated that textiles representing well over US$100 billion in value are lost annually through under-use and inadequate recovery — the precise inventory pool that resale infrastructure is designed to recapture. These are the figures to test against management guidance, not runway applause.
Balance Sheets Before Brand Books
Independent retailers should stop treating a passport as a printing exercise and begin treating it as a data contract: require suppliers to deliver composition and assembly records in a structured format before purchase orders are released, not after delivery. Resale-adjacent businesses — cleaners, cobblers, consignments — should register for buyback partnerships now, while concession terms remain negotiable. Consumers carrying investment-grade leather goods should retain original receipts, dust bags and service history, because residual value is increasingly calculated on documentation as much as condition. Anyone sourcing private-label apparel should diversify across at least two customs jurisdictions before committing a seasonal buy; tariff arbitrage is no longer a finance-team problem.
The Next Two Seasons
Within six months expect three observable adjustments. First, creative announcements will be increasingly paired with distribution announcements — a new name at the studio accompanied by a reduction in wholesale doors. Second, passport compliance will become a visible procurement filter, and non-compliant supplier capacity will reprice downward before it is formally excluded. Third, the resale channel will migrate from consignment to owned-inventory models, because houses will not surrender margin on their own archive indefinitely. The sector that survives the transition will be the one that has stopped describing itself as a business of desire and started operating as a business of verified assets.
Related Articles

Fashion's Next Balance-Sheet Test Is Still Unverified: An Editorial Hold on Today's Analysis
Oct 26, 2026
The Pit Stop Paradigm: How Regulatory Mandates and UHNW Pivots Are Rewiring the Luxury Fashion Franchise
Oct 26, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account