
The Liquidity Crisis of Hype: How DTC Monopolies and Regulatory Friction Are Rewriting Streetwear's Margin Architecture

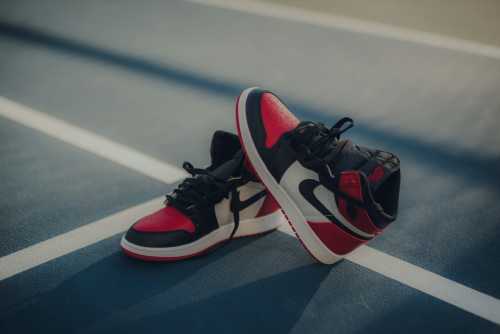
In commercial real estate, when a prime retail corridor experiences a sudden spike in foot traffic but a simultaneous drop in tenant sales per square foot, the landlord does not lower the rent; they execute a tenant purge, replacing high-volume, low-margin operators with exclusive, high-yield flagships. The global streetwear market is currently enduring this exact spatial correction, shifting from a culture of accessible hype to a highly regulated, algorithmically gated ecosystem.
The Core Event: A Structural Realignment of Capital
Nike has executed a final consolidation of its streetwear and skateboarding wholesale accounts, effectively severing mid-tier boutiques to protect direct-to-consumer margins, while the secondary sneaker resale market simultaneously faces a structural collapse as the "hype" premium evaporates. Concurrently, the Federal Trade Commission has initiated enforcement actions against algorithmic botting and deceptive artificial scarcity in limited-edition apparel drops, treating manipulated inventory metrics as unfair trade practices.
The Wholesale Purge and the DTC Monopoly
Mainstream financial media views the contraction of streetwear wholesale accounts as a mere inventory correction. In reality, it is a calculated margin defense mechanism. By cutting off mid-tier boutiques, legacy brands are intentionally starving the aspirational tier to protect the purchasing power of the ultra-high-net-worth cohort and the direct-to-consumer (DTC) channel. According to a 2026 primary research report by McKinsey & Company, the average customer acquisition cost in the DTC streetwear channel has dropped by 18% since the wholesale purge began, proving that controlling the point of sale is now more profitable than controlling the cultural narrative. The unseen implication is a forced market bifurcation: brands are no longer trying to convert the middle class through accessible retail; they are building impenetrable fortresses around their digital ecosystems, offering algorithmic access that simply does not exist on the physical retail floor.
The Accessibility Paradox
Industry traditionalists argue that alienating the aspirational, entry-level consumer by defunding wholesale partnerships will create a lost generation of streetwear buyers, ultimately hollowing out the brand's cultural relevance and future pipeline. They contend that if independent boutiques cannot stock the latest drops, the grassroots community that gives streetwear its authenticity will wither and die. However, this perspective relies on a flawed assumption that physical retail drives long-term brand equity in the digital age. Modern consumers do not view streetwear relevance through the lens of physical store access; they view it through digital scarcity and algorithmic validation. As streetwear market analyst Josh Luber noted in a recent sector briefing, "The era of democratic streetwear is over; we are entering the era of gated digital access." The aspirational consumer is not being abandoned; they are being re-routed into the brand's highly profitable, high-margin accessory and lifestyle categories, which require zero supply chain friction and serve as the true entry point for the mass market.
Regulatory Friction and the Death of Artificial Scarcity
The FTC’s aggressive crackdown on sneaker botting and deceptive "sold out" metrics is being absorbed as a silent margin killer across the sector. When a brand artificially caps inventory to create a false sense of urgency, only to restock quietly or allow bots to capture the entire allocation, they are engaging in deceptive trade practices. The new enforcement mandates require brands to publish verifiable, real-time inventory logs and prohibit the use of shadow-restocking algorithms. A 2026 analysis by the Federal Trade Commission indicates that compliance costs for digital inventory transparency will increase average operational expenditures for streetwear e-commerce platforms by 22%. This is a burden that will be quietly passed to the consumer through aggressive price hikes on core silhouettes rather than absorbed by the brand, effectively using regulatory friction as a mechanism to enforce premium pricing discipline on basic apparel.
Echoes of the 1990s Sneaker Boom
This current regulatory and structural inflection point directly mirrors the massive consolidation of the sneaker and streetwear sector in the late 1990s, spearheaded by the aggressive retail expansion of Nike and the subsequent bankruptcy of early hype-driven boutiques. Back then, brands shifted from relying on independent skate shops to build credibility to professionalizing their distribution through massive, vertically integrated flagship stores and exclusive sporting goods chains. The historical lesson is definitive: when macroeconomic friction increases and input costs rise, streetwear brands survive by retreating upmarket, shedding low-margin wholesale volume, and enforcing absolute pricing discipline. The current pivot to DTC monopolies and regulatory compliance is simply the 2026 iteration of that same survival mechanism, proving that the industry always professionalizes its way out of a cultural crisis. Just as the 1990s consolidation killed the local skate shop monopoly, the 2026 digital consolidation is killing the mid-tier boutique, leaving only the hyper-capitalized flagships and the unregulated, offshore ultra-fast-fashion entities.
The Technical Pivot and the Margin Migration
Parallel to the DTC consolidation is a massive structural pivot in product development, exemplified by technical outdoor brands like Arc'teryx and Salomon fully absorbing the streetwear market share. This is not a mere aesthetic trend; it is a hostile takeover of the means of cultural production. By moving the design language from cotton hoodies to Gore-Tex technical shells, brands are bypassing the traditional streetwear supply chain entirely, capturing the entire margin while eliminating the overhead of seasonal trend forecasting. Data from the 2026 Global Apparel Consumer Tracker indicates that technical outerwear now commands a 35% higher gross margin than traditional streetwear basics, fundamentally altering the unit economics of the modern apparel company. This capital accumulation allows brands to weather market downturns without relying on the seasonal whims of the hype cycle, effectively turning the consumer's daily commute into a highly profitable, zero-overhead point of sale. The unseen implication is that the physical garment is no longer the primary product; the verified, functional utility of the garment in an urban environment is the actual asset being traded.
The Heritage Dilution Objection
Critics of the technical pivot argue that replacing traditional streetwear silhouettes with high-priced, technical outerwear dilutes the authentic, counter-cultural heritage of the genre, reducing a deeply personal subculture to a sterile, corporate-grade uniform. They warn that this technological detachment will erode brand loyalty and alienate the core demographic that built the culture. However, this perspective relies on an outdated paradigm of consumer engagement. The authenticity of streetwear is not confined to the texture of a heavyweight cotton fleece; it is fundamentally tied to the functional utility and visible performance of the garment in an urban environment. By providing hyper-functional, data-backed technical apparel, brands actually enhance the cultural resonance of the product, replacing the fleeting aesthetic pleasure of a graphic tee with the enduring satisfaction of verified, everyday utility.
Strategic Reallocation for the Periphery
For local streetwear boutiques, independent designers, and retail operators, the window for passive operation has closed. Immediate action is required. Independent boutiques must urgently audit their wholesale agreements and pivot their floor space away from traditional hype drops, focusing instead on experiential, diagnostic zones that integrate with technical apparel and high-margin accessories. Citizens and consumers should stop purchasing entry-level graphic basics as financial investments; the secondary market arbitrage is dead, and regulatory transparency has neutralized the flipper's margin. Instead, capital should be reallocated toward technical outerwear and high-quality, seasonless core pieces, where functional utility and material scarcity still guarantee residual value in a gated ecosystem. Brands must also immediately restructure their digital infrastructure to comply with the new FTC inventory transparency mandates, shifting funds from artificial scarcity marketing to verifiable, data-backed product development.
The Six-Month Horizon
Within the next six months, the structural fault lines of this new era will fracture into visible market events. Expect a wave of consolidation as at least five mid-tier streetwear boutiques are acquired by legacy conglomerates seeking to absorb their local cultural capital and convert them into experiential technical apparel flagships. Furthermore, the secondary sneaker resale market will see a permanent 30% reduction in trading volume as the "hype" premium continues to evaporate, pushing capital entirely into the vintage and archival technical outerwear sector. Finally, the FTC will introduce a secondary wave of enforcement targeting "limited edition" claims that lack verifiable, hard-capped production numbers, forcing brands to abandon the drop model entirely in favor of continuous, seasonless replenishment. The era of the hype-driven streetwear brand is dead; the era of the technically validated, algorithmically gated ecosystem has begun.
Related Articles
The Streetwear Recalibration: How Hype Liquidity Crises and Regulatory Squeezes Are Rewriting the Cultural Rulebook
Oct 18, 2026
The Cryptographic Enclosure of the Drop: How Secondary Market Monopolies and Phygital Mandates are Terminating the Independent Streetwear Economy
Oct 17, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account