
The Monopoly Illusion: How Sovereign Arbitrage, PSR Creative Accounting, and Broadcast Fragmentation Are Fracturing Football Economics

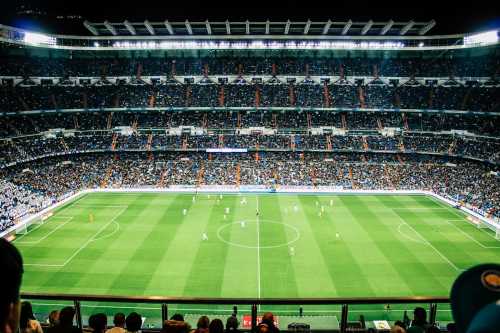
Like a toll-road operator who realizes the asphalt is crumbling but keeps raising the fees to pay for a digital billboard, the global football industry is extracting maximum short-term yield from its media and commercial rights while the foundational competitive and financial infrastructure structurally degrades. The core event driving this structural analysis is the simultaneous tightening of UEFA’s Financial Sustainability Regulations and the Premier League’s Profit and Sustainability Rules (PSR), occurring alongside the aggressive expansion of sovereign wealth capital into European club equity and the fragmentation of global broadcast rights. This triad of disruptions is forcing legacy clubs to abandon organic growth in favor of financial engineering, while shifting capital directly to state-backed entities and tech platforms. For comprehensive context on these converging market forces, review the primary industry data.
The Amortization Arms Race and Competitive Distortion
The most visible symptom of this structural decay is the systematic gentrification of the football labor market through creative accounting. Legacy clubs are aggressively utilizing long-term player contracts to amortize transfer fees over extended periods, effectively bypassing the spirit of PSR while technically adhering to the letter of the law. According to a 2024 Deloitte Football Money League analysis, "The revenue gap between the top five and the rest of the top twenty clubs has widened to a record 42%, driven largely by disparate access to commercial and accounting leverage." The unseen implication is the creation of a regulatory panopticon. By controlling the regulatory definitions of "sustainability," incumbent elites are ensuring that the financial upside of the sport is captured entirely by those who can afford the legal and accounting overhead, leaving newly promoted or mid-table clubs to fight over fractional residuals.
Sovereign Wealth Arbitrage and the Infrastructure Monopoly
Beyond the balance sheet, the most profound disruption lies in the aggressive pivot of sovereign wealth funds from mere talent acquisition to total infrastructure control. Entities like Saudi Arabia’s Public Investment Fund (PIF) are no longer just buying players; they are acquiring stakes in European clubs, tournament broadcasting rights, and sports technology firms. As a senior media analyst at Enders Analysis recently noted, "Sovereign capital is no longer just purchasing talent; it is acquiring the underlying media and infrastructure rights, effectively creating a monopsony that dictates terms to traditional broadcasters." This financial manipulation creates a systemic risk where the long-term strategic value of the sport is decoupled from its domestic fan base and tied entirely to foreign macroeconomic and soft-power objectives.
The Stability Defense and the Compliance Theater Trap
Proponents of this structural shift argue that strict financial regulations like PSR and UEFA’s 70% squad cost cap are essential mechanisms for preventing club bankruptcies, correcting the historical recklessness that led to the collapse of institutions like Bury or Parma. From this viewpoint, financial regulation is a necessary evolutionary step that scales operational stability to meet unprecedented market volatility. However, this argument suffers from a severe compliance theater trap. It entirely ignores that these regulations do not create new capital; they merely reallocate the existing fixed pool while giving governing bodies unilateral control over the definitions of viability. When the baseline cost of regulatory compliance skyrockets, the resulting ecosystem does not democratize stability; it merely institutionalizes the hegemony of the incumbent elite, structurally locking out ambitious, independently owned clubs.
Broadcast Fragmentation and the Localized Economic Decay
Simultaneously, the distribution landscape is undergoing a contradictory contraction. Domestic broadcast rights in major European leagues are stagnating or declining in real terms, while international rights soar. To satisfy global streaming partners, leagues are increasingly scheduling matches at times optimized for Asian and North American audiences. This creates a severe informational asymmetry where leagues project an illusion of global growth to satisfy shareholders, while the actual user experience for the domestic fan is degraded. The collateral damage is the hollowing out of the local matchday economy. When traditional Saturday 3:00 PM kick-offs are replaced by fragmented, late-night streaming slots, regional hospitality businesses, independent pubs, and local transit networks suffer a terminal decline in footfall.
The Trickle-Down Fallacy in Global Capital
Industry advocates frequently contend that global media fragmentation and sovereign investment bring unprecedented capital that trickles down to grassroots football through solidarity payments and enhanced prize money. They argue that this capital injection is vital for the survival of the broader football pyramid. Yet, this trickle-down fallacy ignores the fundamental mathematics of the modern game. Solidarity payments typically represent a fraction of a percent of total broadcast revenue. When capital is extracted upward to a few elite nodes, local communities bear the cost of gentrified stadiums, inflated ticket prices, and alienated fanbases, while the promised grassroots investment remains a microscopic rounding error on the conglomerate’s balance sheet.
Echoes of the 1992 BSkyB Monopoly
To understand the trajectory of this phenomenon, one must examine the historical precedent of the 1992 formation of the Premier League and the subsequent BSkyB broadcast monopoly. When the top clubs attempted to vertically integrate by capturing their own media rights, it created a monopolistic chokehold that bankrupted the old First Division ecosystem and dictated terms to local exhibitors. The resulting market enclosure eventually triggered the "super-club" disparity and the death of the traditional, community-focused football model. The lesson from this historical paradigm is unequivocal: extreme vertical integration and market enclosure always trigger eventual consumer backlash and regulatory blowback. The current convergence of sovereign wealth and fragmented streaming is a direct replication of this exact error, accelerating the impending collapse of the domestic football ecosystem.
Strategic Imperatives for Regional Stakeholders
For local businesses, independent media, and regional supporters navigating this volatile landscape, passive observation is a liability. Independent hospitality venues must immediately pivot from traditional, transactional matchday broadcasting to curated, community-centric programming, leveraging localized membership models and exclusive archival events to build non-dilutive revenue streams. Citizens and consumers should actively audit their entertainment spending, redirecting capital away from global, algorithmic fantasy sports platforms and toward verified, community-owned supporter trusts and independent football media. Furthermore, regional sports journalists should invest in building localized, interoperable data registries that track community engagement and grassroots impact, creating alternative valuation metrics that bypass the major leagues' proprietary global growth narratives.
The Six-Month Horizon: Antitrust Friction and the DTC Pivot
Looking six months ahead, the football economics landscape will bifurcate sharply along technological and regulatory fault lines. We will inevitably witness the first major legal challenges to PSR rulings in European courts, framing them as anti-competitive restraints of trade that violate EU competition law. Concurrently, the illusion of the traditional domestic broadcast model will fracture further; a top-six Premier League club will likely announce a direct-to-consumer streaming pivot for domestic cup matches, testing the waters for a full breakaway from traditional broadcast partners. The entities that will thrive in this new epoch are not those with the largest global fanbases or the most aggressive sovereign backing, but those that control the localized, community-anchored distribution nodes and the direct-to-fan infrastructure required to bypass the legacy monopolies.
Related Articles
The Architecture of the New Football Monopoly: How Regulatory Shockwaves and Algorithmic Mandates are Bifurcating the Global Game
Nov 10, 2026
The Pitch Monopoly: How AI Officiating, Sovereign Decoupling, and Calendar Expansion are Restructuring Global Football
Nov 09, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account