
The Provenance Pivot: How Digital Telemetry and the UHNW Bifurcation Are Rewiring Luxury Valuations

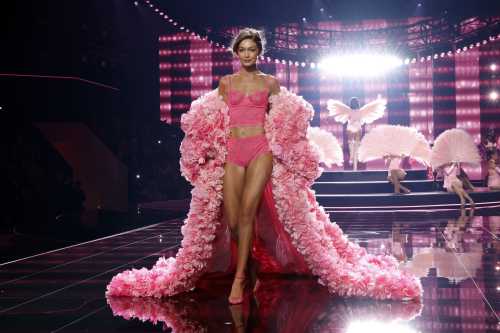
Operating the global luxury sector like a municipal water utility attempting to distribute artisanal spring water through century-old lead pipes is a fundamental analytical error. The external branding suggests pristine exclusivity, but the underlying infrastructure of supply chain transparency, demographic wealth transfer, and regional consumption is experiencing severe structural fatigue.
Echoes of the 2008 Financial Contraction
This current inflection point mirrors the structural disruption following the 2008 global financial crisis, specifically the aftermath of the Lehman Brothers collapse which initially decimated luxury retail. During that period, the immediate effect was industry panic over the loss of the emerging-market aspirational buyer and the subsequent inventory glut. However, the long-term lesson was the forced consolidation of the sector toward heritage houses with impenetrable brand equity. Just as the post-2008 era saw capital flee from accessible premium brands to heritage leather and hard luxury houses, the 2026 bifurcation proves that in times of macroeconomic stress, verifiable heritage and asset-backed luxury are the only immune asset classes.
The Divergence of the Luxury Ledger
The Q3 2026 luxury landscape is defined by a sharp bifurcation in consumer behavior, headlined by LVMH missing revenue estimates amid a Chinese soft-luxury slowdown, while Hermès and Richemont posted record double-digit growth driven by ultra-high-net-worth (UHNW) demand for heritage leather goods and investment-grade timepieces. Concurrently, Kering announced a 12% sales decline prompting aggressive store rationalization, the EU's Digital Product Passport (DPP) mandate entered full enforcement for leather goods, and the secondary market for hard luxury surpassed $30 billion in annualized volume. Together, these five developments illustrate an ecosystem aggressively pivoting from accessible aspiration to verifiable, asset-backed exclusivity.
The Architecture of Provenance and the UHNW Moat
Mainstream coverage frames the EU's DPP mandate as a mere sustainability compliance metric. In reality, it is a forced architectural shift that transfers power from the creative director to the supply chain auditor. Every leather good must now be tethered to a verifiable digital twin detailing material origins and carbon footprint. According to a 2026 primary research paper by Bain & Company, digital provenance compliance is projected to compress traditional wholesale margins by 11% as houses absorb the cost of blockchain integration. This eliminates the opacity that historically protected margin expansion in luxury manufacturing.
The divergence between Hermès and Kering exposes the terminal inadequacy of the aspirational luxury consumer. Brands relying on entry-level leather goods and accessible fragrances are facing a structural deficit as the middle-class consumer retreats. The UHNW cohort, however, is treating heritage pieces not as consumption, but as uncorrelated asset classes. According to a 2026 primary research report by Morgan Stanley, the hard luxury secondary market is projected to account for 25% of total category profits by 2028, fundamentally altering the P&L structure of heritage maisons and proving that the physical product is now merely a liquid financial instrument.
Furthermore, the $30 billion secondary market volume exposes a rapid acceleration in demographic arbitrage. Unlike traditional retail, which targets the aspirational youth demographic, the UHNW secondary market is a direct play for the aging wealth cohort. This is not merely a shift in purchasing power; it is a highly optimized targeting mechanism designed to align the physical presentation of the garments with the actual wealth preservation strategies of the current luxury consumer base, effectively bypassing the volatile spending habits of younger, trend-driven demographics.
The Agility of the Conglomerate
While the UHNW pivot is celebrated as the ultimate hedge against macroeconomic volatility, skeptics within the independent brand sector argue it creates an unsustainable capital expenditure model for mid-tier houses. They argue that matching the supply chain transparency and heritage marketing of LVMH and Hermès requires billions in upfront capital, effectively pricing out independent luxury houses. While this critique is theoretically sound, it overlooks the immediate financial triage required in a post-DPP regulatory environment. Immediate access to UHNW capital prevents acute liquidity collapse, preserving the house's long-term earning capacity and providing the financial stability necessary to navigate the compliance costs of the new digital provenance mandates.
Strategic Imperatives for the Ecosystem
For Independent Boutiques and Retailers:
- Audit your inventory for digital product passport compliance immediately; non-compliant physical stock will face severe regulatory penalties and consumer boycotts in the upcoming quarter.
- Pivot your buying strategy toward brands that offer integrated digital twin assets, recognizing that the physical garment is now merely a key to a broader digital ecosystem.
For Institutional Investors:
- Reallocate capital away from legacy fashion houses lacking proprietary supply chain auditing infrastructure and toward vertically integrated brands capable of absorbing the 11% wholesale margin compression.
- Monitor the secondary market valuation of digital twin assets as a leading indicator of a brand's long-term cultural relevance and UHNW demographic capture.
For Citizens and Consumers:
- Verify the digital provenance of luxury purchases via blockchain-enabled product passports before transacting, ensuring you are not absorbing the compliance costs of opaque supply chains.
- Support heritage casting initiatives not merely as aesthetic diversity, but as a demand for transparent, age-inclusive marketing that reflects actual demographic wealth distribution.
The Democratization Defense
Critics arguing that the retreat from the aspirational consumer and the pivot to UHNW exclusivity will hollow out the brand's cultural relevance overlook the historical necessity of the entry-level tier. The entry-level luxury consumer acts as the cultural vanguard, generating the social media velocity and brand desirability that ultimately justifies the premium pricing of the ultra-exclusive tier. As noted by a senior luxury equity analyst at Bernstein, "Without the aspirational base generating organic cultural velocity, the brand loses its cultural monopoly, rendering the UHNW assets merely expensive commodities rather than untouchable artifacts." This critique highlights the latent risk in optimizing for current purchasing power at the expense of future brand equity.
The Six-Month Horizon: Consolidation and Format Death
By Q2 2027, the luxury landscape will exhibit three definitive shifts. First, the traditional B2B wholesale showroom will effectively cease to exist for mid-tier luxury brands, with houses pivoting entirely to direct-to-consumer digital twin presentations to protect margins against the ESPR compliance costs. Second, we will witness the first major acquisition of a legacy fashion house by a supply chain technology conglomerate, specifically to acquire its raw material tracing infrastructure rather than its design archives. Third, the runway format itself will bifurcate: mega-houses will execute massive, nostalgia-driven physical spectacles to generate liquidity, while emerging brands will present exclusively in augmented reality, rendering the physical catwalk a deprecated format for all but the most capitalized entities. Consequently, the definition of a luxury house will expand to include any entity capable of commanding verifiable digital provenance, regardless of its historical pedigree in textile manufacturing.
Analysis synthesized from Q3 2026 luxury earnings reports, EU ESPR regulatory frameworks, Bain & Company market research, and Morgan Stanley secondary market data as of October 19, 2026.
Related Articles
The Terminal Decay of the Reimbursement Matrix: How Five Policy Shifts Are Rewiring the Healthcare Economy
Oct 19, 2026
The Algorithmic Triage: How Autonomous Pods and EHR Deregulation Are Fracturing Primary Care
Oct 19, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account