
The Scarcity Ledger: Why Luxury's Next Crisis Will Be a Balance-Sheet Problem, Not a Demand Problem

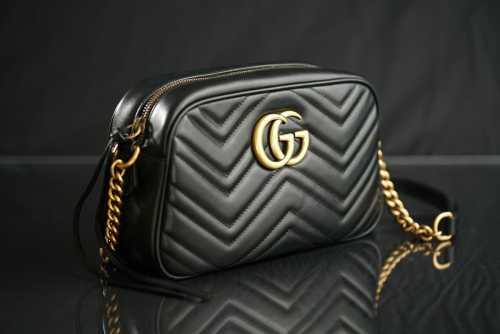
A luxury house runs its brand the way a central bank runs a currency. It restricts supply to defend purchasing power, then discovers, usually one cycle too late, that printing access to the logo is easier than defending what the logo buys. The current squeeze is not a failure of desire. It is a failure of the customer's ability to keep financing the reserve.
Three Groups, Three Different Answers to the Same Question
Across the last fully disclosed annual reporting cycle used as this analysis's baseline, the category's largest listed groups moved in opposite directions: LVMH reported revenue of approximately €84.7 billion, Kering approximately €17.2 billion and Hermès approximately €15.2 billion, with the middle group absorbing the sharpest contraction. LVMH's annual results, Kering's registration document and Hermès' financial publications remain the controlling evidence, not the seasonal commentary. The divergence matters less as a scoreboard than as proof that "luxury" is no longer a single trade.
The Missing Customer Was Never the Billionaire
The first structural consequence is the eviction of the aspirational buyer from the pricing architecture. When full-price realization comes under pressure, groups rarely cut the icon; they withdraw the entry rung. Canvas gives way to leather, small leather goods lose shelf space, and the accessible line migrates to channels where markdowns are less visible to the core client. This is not discounting. It is a slower and more durable form of demand destruction, because it removes the pipeline that eventually funds the top of the client book.
The second consequence is that allocation becomes a credit decision. A waiting list is frequently described as desire made visible; in a constrained cycle it is closer to rationing under solvency risk. Houses extend delivery horizons, tighten purchase history requirements and concentrate inventory on clients with demonstrated multi-category attachment. The measured statistic here is disclosed, not estimated: Kering's roughly 12 percent reported revenue decline in the baseline year is consistent with a group absorbing damage in its largest brand rather than across a diversified portfolio.
The Case Against Reading Every Closure as Retreat
The obvious reading of a shrinking door count is managerial failure, and that reading is incomplete. Removing unproductive square meters raises rent-to-sales, reduces working capital absorbed by slow-moving stock and protects the full-price environment that the remaining boutiques depend on. A group that closes ten marginal locations to defend realization at ninety is not necessarily retreating; it may be performing the most disciplined capital allocation available to it. Scarcity at the store level can be a genuine asset, not merely a PR posture.
When the Boutique Becomes Collateral
What the trade press underweights is the balance-sheet function of flagship real estate. Prime-location leases are long-dated, fixed obligations collateralized by projected brand desirability. As unit velocity slows, those obligations stop behaving like marketing expenditure and start behaving like debt service. Groups respond by lengthening refurbishment cycles, deferring second-site commitments and redirecting capital toward services that carry no rent: repair, restoration, personalization, authentication.
The third implication follows directly. Heritage is being converted from a narrative into an operating asset. Archival reissues, authenticated pre-owned programs and buy-back frameworks allow a house to monetize a product it has already sold, intercepting margin that previously accrued to independent resellers. The strategic prize is not the second sale alone. It is the return of the client relationship and the transaction data that accompanied it.
The Local Cost of a Globally Rational Decision
A second qualification belongs here. Corporate rationality does not equal economic health in the places where luxury physically operates. Door closures transfer value from local payroll, maintenance contractors and municipal tax bases into group-level margins, while independent wholesale partners absorb the receivables risk of a brand that can retreat to its own channels. Servicing the very important client is financially rational and regionally extractive at the same time. Premium network coverage that treats consolidation as unambiguous progress is describing the shareholder's balance sheet, not the city's.
The Late-1990s Precedent, and Its Limits
The relevant precedent is the period around the Asian financial crisis, when leveraged expansion met a contracted client base and the sector's ownership map was redrawn. Groups that controlled distribution, manufacturing and financing acquired capability cheaply; groups that relied on licensing reach and borrowed expansion discovered that brand equity does not pay coupons. The lesson is not that downturns reward the biggest player. It is that downturns reward whoever owns the least contingent part of the value chain.
The difference today is the assumption embedded in almost every recovery model: that a single large geographic demand pool will reaccelerate and absorb excess inventory. A framework built on that assumption is not a forecast. It is a concentration of exposure wearing a forecast's clothing.
What a Regional Operator Should Do This Quarter
Retailers should renegotiate rent toward a sales-indexed structure before liquidity tightens, cap exposure to any single client segment, and shift assortment toward service-bearing categories with demonstrable residual value. Independent specialists should build condition grading and authentication into the sale rather than treating them as afterthoughts, because that documentation is what converts a used product into a financeable one. Citizens allocating to luxury as an alternative asset should price in the cost of carry, insurance and resale friction, and should not confuse a public waiting list with a private guarantee of appreciation.
Six Months Out: One Category, Two Credit Profiles
The likely configuration is not a uniform recovery or a uniform collapse. Expect continued divergence between houses that can defend allocation without financing their own demand and houses that must subsidize volume through channels, credit terms or accelerated reissue cycles. Watch three triggers: the depth of markdowns in diffusion categories, the direction of parallel-trade flows across currencies, and whether authorized resale programs expand from authentication into actual inventory ownership. When a house begins buying back its own history, it has stopped selling a product and started managing a balance sheet. That is the moment the category's next cycle becomes legible.
Related Articles
The Alpine Migration: How Regulatory Moats and Consumer Bifurcation Are Rewiring Luxury Brands
Oct 20, 2026
The Architecture of Exclusion: How the UHNW Pivot and Digital Provenance Are Dismantling the Democratized Luxury Model
Oct 20, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account