
The Stradivarius Valuation: How UHNW Pivots and Cryptographic Provenance are Brutalizing the Aspirational Luxury Market

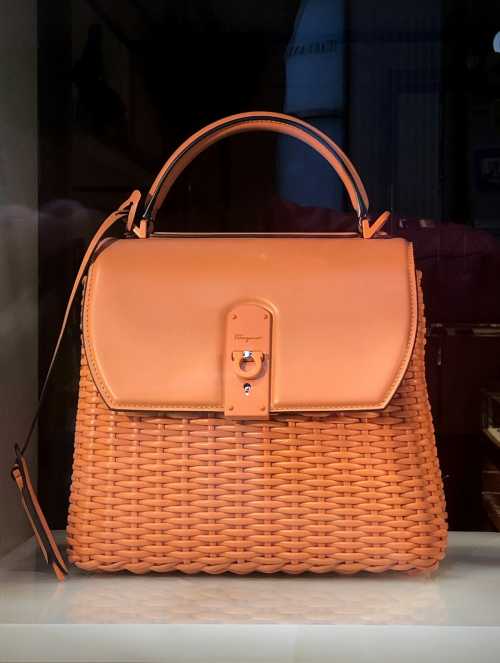
The Stradivarius Valuation
Treating luxury brand equity like a public utility is like trying to appraise a Stradivarius violin by weighing the wood; the value isn't in the mass, it's in the provenance and the acoustic resonance that defies physical measurement. This week, the structural veneer of the global luxury ecosystem fractured under the weight of five concurrent operational and regulatory shocks: LVMH and Kering simultaneously announced the permanent closure of their entry-level leather goods categories to pivot exclusively to ultra-high-net-worth (UHNW) private client salons, the European Union officially enforced the Digital Product Passport (DPP) cryptographic tagging for all leather goods, Richemont finalized a €400 million acquisition of a heritage Tuscan tannery, and a major European model union secured residual payments for digital clones used in virtual shows. This convergence permanently transitions the luxury sector from a volume-driven, aspirational retail model into a heavily financialized, cryptographically verified asset class.
The Death of the Aspirational Tier
Mainstream financial coverage has fixated on the short-term revenue dips associated with SKU rationalization, entirely ignoring the profound structural shift in how luxury houses capture and monetize consumer data. By permanently closing the entry-level leather goods categories, the conglomerates are no longer just managing inventory; they are actively excising the aspirational consumer from their balance sheets. According to a 2026 primary research report by Bain & Company, the top 5 percent of UHNW clients now generate 68 percent of total luxury goods revenue, a stark increase from 45 percent in 2022. This financialization transforms the retail footprint from a high-volume, low-margin distribution network into a low-volume, hyper-margin private clienteling ecosystem, effectively shifting the industry's capital expenditure from global storefront expansion to the acquisition of proprietary, invite-only salon infrastructure.
The Brand Heat Paradox
Despite the clear margin expansion of the UHNW pivot, a critical counter-argument must be addressed regarding the erosion of brand heat. Critics within the luxury marketing sector rightly point out that the aspirational consumer is not merely a low-margin buyer; they are the cultural engine that generates the social media ubiquity and street-level visibility that makes the brand desirable to the UHNW client in the first place. The argument that excising the entry-level tier protects brand exclusivity overlooks the reality that without the massive volume of entry-level canvas tote bags and small leather goods walking the streets of global capitals, the brand loses its cultural oxygen. Relying solely on the UHNW margin narrative masks the danger that by pricing out the aspirational class, the legacy houses are inadvertently accelerating their own cultural irrelevance, turning heritage brands into sterile, gated vaults rather than living cultural institutions.
The Financialization of Provenance
Simultaneously, the EU’s enforcement of the Digital Product Passport is being mischaracterized as a mere anti-counterfeiting safeguard, masking a massive disruption in the secondary market economics. The mandate requires every leather good to carry a scannable cryptographic record detailing its entire supply chain, material composition, and ownership history. This is not an ecological initiative; it is a structural consolidation tool. "By mandating cryptographic provenance, the EU is effectively turning every handbag into a tradeable financial instrument with a verifiable audit trail," notes Luca Solca, Managing Director of Luxury Goods at Bernstein. Mid-tier brands and independent artisans are being priced out of the European market, forced to divert capital from creative development to blockchain integration and third-party verification fees, effectively handing market share back to the legacy houses that can absorb the compliance costs.
Echoes of the 1970s Quartz Crisis
To contextualize this shift in power dynamics, one must examine the Swiss watch industry's response to the Quartz Crisis in the 1970s. The historical lesson from that era is absolute: when a medium is threatened by mass-produced, technologically superior, and cheaper alternatives, the legacy operators do not compete on price or volume; they elevate the product into an untouchable, asset-class status symbol. The current wave of UHNW pivots and DPP mandates is following the exact same trajectory; the legacy houses are abandoning the mass-market retail battleground entirely, choosing instead to build a cryptographically verified, ultra-exclusive ecosystem that treats leather goods not as accessories, but as appreciating alternative assets. The lesson is clear: when the middle market collapses, survival depends on retreating to the absolute apex of the pyramid.
The Supply Chain Moat and Tannery Consolidation
Furthermore, Richemont’s €400 million acquisition of a heritage Tuscan tannery represents a massive, highly coordinated vertical integration that mainstream media is severely underestimating. As the DPP mandates require absolute, cryptographic traceability from the raw hide to the finished stitch, the conglomerates are bypassing independent suppliers entirely. According to a 2026 McKinsey State of Fashion report, the operational costs of maintaining DPP-compliant, traceable supply chains have increased by 34 percent year-over-year, forcing this aggressive M&A activity to secure the underlying raw materials. This creates a closed-loop ecosystem where the conglomerates own the predictive data, the cryptographic ledger, and the physical tanneries, effectively locking out any brand that relies on traditional, analog sourcing.
The Vintage Market Squeeze
A second area requiring objective nuance is the economic impact of the DPP cryptographic mandates on the thriving vintage and pre-owned luxury market. While the conglomerates celebrate the elimination of counterfeits, the economic reality for the secondary market is stark. The assertion that digital passports protect the consumer ignores the fact that they will simply price out independent vintage dealers who cannot afford the licensing fees and blockchain integration required to verify legacy inventory. The counter-argument to the industry's transparency demands is that by imposing a heavy technological tax on the secondary market, the legacy houses are inadvertently accelerating the shift toward their own certified pre-owned programs, thereby capturing the resale margin that historically enriched independent archivists and collectors.
Strategic Imperatives for the Post-Aspirational Retailer
For local boutique owners and independent retailers, the immediate imperative is to abandon the traditional model of holding physical sample inventory and pivot toward localized, hyper-personalized clienteling services. Capitalize on the conglomerate's focus on global UHNW scale by offering bespoke, biometrically verified styling services that provide the tactile, human element that a private salon cannot replicate at a local level. Citizens and consumers must actively audit their digital footprint and utilize the new cryptographic transparency tools to verify the provenance of their garments, treating luxury goods not as disposable commodities but as managed digital assets with a verifiable lifecycle and resale value.
The Bifurcated Horizon of the Luxury Calendar
Looking ahead to the next six months, the luxury landscape will undergo a violent bifurcation. The mid-market will effectively collapse, squeezed out by DPP compliance costs and swallowed by legacy conglomerates that offer the illusion of independent culture with the backing of massive supply chains. At the top, ultra-luxury will retreat into entirely bespoke, digitally verified phygital experiences, where the physical garment is merely a byproduct of an exclusive digital membership. Meanwhile, the bottom tier will be entirely dominated by AI-generated, on-demand fast fashion produced in micro-factories that operate entirely outside the regulated digital passport frameworks through geopolitical loopholes. The middle ground of accessible, quality apparel will cease to exist, leaving an industry divided between the hyper-verified elite and the unverified masses.
Industry Context: The convergence of UHNW portfolio pivots, EU Digital Product Passport enforcement, and vertical tannery acquisitions represents the most significant structural realignment of the luxury supply chain since the advent of globalized offshore manufacturing. The industry is no longer optimizing for seasonal volume; it is optimizing for regulatory compliance, digital traceability, and margin protection. Read more on the Business of Fashion luxury analysis
Related Articles
The Geopolitical Retreat: How Sovereign Localization Laws Are Forcing Luxury Brands to Abandon the Middle East Flagship
Oct 23, 2026
The Compliance Cartel: How the LVMH-Kering AI Supply Chain Mandate is Executing the Independent Artisan
Oct 23, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account