
The Fiat Standard of Couture: How Digital Provenance and Secondary Markets Are Rewriting Fashion Economics

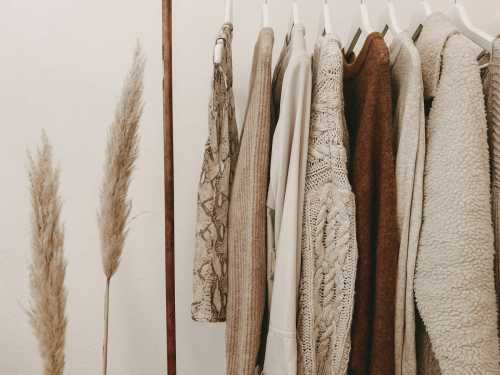
Just as the 1971 Nixon shock decoupled the US dollar from physical gold, forcing central banks to manage perception and liquidity rather than physical reserves, the global fashion industry is experiencing its own monetary reset. The mandatory implementation of Digital Product Passports (DPP) under the EU’s Ecodesign for Sustainable Products Regulation (ESPR) is decoupling luxury value from physical scarcity, forcing heritage houses to manage algorithmic lifecycle data and digital provenance.
The Provenance Paradigm Shift
The European Union has officially activated the regulatory framework requiring Digital Product Passports for all textiles and footwear sold within its borders, mandating granular supply chain transparency. Concurrently, the luxury resale sector has crossed the threshold of a 25% market share penetration in key Asian demographics, fundamentally altering primary market pricing power. This dual catalyst is not merely a regulatory adjustment; it is a structural rewriting of fashion economics, shifting the industry's foundational value metric from physical material scarcity to verifiable digital lineage.
The Margin Compression of Mandatory Transparency
Mainstream coverage focuses heavily on the environmental benefits of the ESPR, entirely missing the severe margin compression it forces upon legacy houses. Tracking raw material origins, chemical usage, and labor conditions requires a complete overhaul of legacy ERP systems and supplier contracts. A 2026 report by the European Commission estimates that implementing Digital Product Passports will increase operational costs for mid-tier apparel brands by 12-15% in the first year alone. This is not a transient marketing expense; it is a permanent structural tax on the cost of goods sold.
As Luca Solca, Managing Director of Luxury Goods at Bernstein, noted, "Transparency is no longer a marketing exercise; it is a structural cost that will permanently alter the P&L of legacy houses." This reality dictates that brands unable to absorb these costs will face an existential choice: compress margins to maintain price parity, or pass the costs to consumers and risk volume erosion.
The Secondary Market Cannibalization and the Acquisition Funnel
The explosion of the secondary market is actively cannibalizing the entry-level luxury segment. According to Bain & Company, the global personal luxury goods market is projected to reach €400 billion by 2026, yet the secondary market is growing at three times the rate of the primary market. Consumers are systematically bypassing traditional retail markups, opting for authenticated pre-owned goods on platforms like The RealReal and Vestiaire Collective. This dynamic severely limits the pricing power of heritage brands at the entry tier, forcing a reevaluation of how initial product value is captured.
However, framing this purely as a threat to primary revenue ignores the sophisticated customer acquisition mechanics at play. The secondary market functions as a highly effective, zero-CAC (Customer Acquisition Cost) funnel. By circulating pre-owned goods, brands introduce their heritage and aesthetic to younger, price-sensitive demographics who are statistically highly likely to graduate to primary market purchases as their disposable income increases. The resale market is not a competitor; it is an unpaid, decentralized marketing arm that sustains brand desirability without the associated media spend.
Echoes of the 1980s Japanese Quality Invasion
This structural disruption closely mirrors the Japanese quality invasion of the American automotive and electronics sectors in the 1980s. When Japanese manufacturers introduced rigorous quality control, lean manufacturing, and unprecedented supply chain transparency, legacy American brands initially dismissed them as low-cost imitators lacking brand heritage. Instead, the Japanese redefined the baseline for manufacturing excellence, forcing a brutal consolidation in the US market and permanently altering consumer expectations regarding reliability and data.
Today’s mandated supply chain transparency is the fashion equivalent of that paradigm shift. Brands that view DPP compliance merely as a bureaucratic hurdle will be outmaneuvered by agile, vertically integrated competitors who use data transparency as a core component of their value proposition. Just as Ford and GM were forced to adopt lean principles or face obsolescence, European and American fashion houses must integrate granular supply chain telemetry into their core operational DNA to survive the coming consolidation.
The Algorithmic Authenticity Paradox and the Regulatory Moat
The integration of AI in design and supply chain forecasting is colliding with the consumer demand for verifiable human craftsmanship. As brands deploy generative AI to optimize textile yields and predict trend cycles, the physical garment becomes a hybrid of algorithmic efficiency and human execution. This creates an authenticity paradox where the "story" of the garment is increasingly synthetic, challenging the traditional luxury narrative of artisanal creation. Consumers are beginning to demand transparency not just in materials, but in the very genesis of the design itself.
Conversely, critics argue that these stringent EU regulations will stifle innovation and crush independent designers under the weight of compliance costs, effectively killing the next generation of creative talent. Yet, this regulatory moat actually serves to protect established luxury pricing power. By raising the barrier to entry, the ESPR effectively eliminates ultra-fast-fashion competitors who rely on opaque, high-volume, low-margin models. This insulates heritage brands from bottom-tier price erosion, ensuring that the market remains concentrated among players who can afford the cost of verifiable authenticity.
Strategic Imperatives for the Supply Chain
For Independent Brands: Immediately invest in modular PLM (Product Lifecycle Management) software capable of generating ESPR-compliant data structures. Do not attempt to build proprietary blockchain trackers; utilize existing B2B SaaS infrastructure to maintain agility and minimize capital expenditure.
For Legacy Houses: Restructure the secondary market from a legal threat to a strategic asset. Launch official, brand-certified resale programs to capture the margin on the second and third lifecycle of the product, retaining absolute control over the digital provenance and authentication process.
For Local Retailers: Capitalize on the compliance gap. Curate "fully transparent" collections, using the DPP data as a primary marketing tool to justify premium pricing against e-commerce giants, positioning physical retail as the ultimate destination for verified, tactile authenticity.
The 2027 Provenance Landscape
Within six months, the initial shock of DPP enforcement will trigger a wave of M&A activity across the mid-market sector. Brands lacking the capital to upgrade their supply chain telemetry will become acquisition targets for larger conglomerates seeking to absorb their compliant infrastructure and supplier networks. By mid-2027, the fashion landscape will be strictly bifurcated: a highly consolidated, ultra-transparent luxury tier where digital provenance commands a 30% price premium, and a marginalized, non-compliant tier relegated to unregulated geographic markets. The ultimate currency of fashion will no longer be the logo, but the verifiable data attached to the seam.
Related Articles
The Velvet Squeeze: How Regulatory and Circular Pressures Are Rewiring the Luxury Fashion Monolith
Oct 18, 2026
The Fiat Standard of Fashion: How Digital Mandates and AI Copyright Are Rewiring Apparel Valuation
Oct 18, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account