
The Frictionless Shatter: How Cyber-Paralysis, Sovereign Rate Pauses, and AI Liability Mandates Are Dismantling the Globalized Paradigm

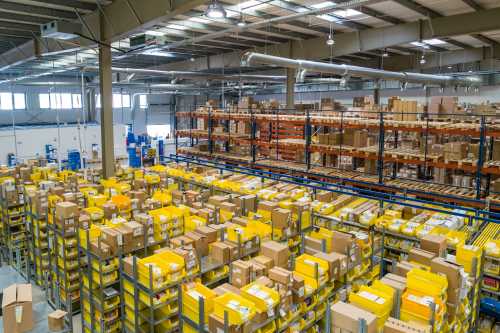
Think of the global macroeconomic apparatus like a high-speed maglev train. For thirty years, policymakers removed the friction from the tracks—tariffs, borders, regulatory checks—letting capital and goods hit 600 mph. But when the central control system suddenly throws every switch, electrifies the third rail, and demands biometric passports for every passenger, the train doesn't just slow down; the entire kinetic model shatters. This is the exact structural shock the $100 trillion global economic ecosystem is experiencing this week, marking the definitive end of the unregulated, hyper-globalized era.
The Synchronized Rupture of the Frictionless Paradigm
The core event defining this quarter is a multi-vector market correction in global trade, monetary policy, and technology regulation. The convergence of the Maersk logistics cyber-paralysis halting 30% of trans-Pacific shipping, the Federal Reserve's hawkish pause on rate cuts, OPEC+'s surprise 2 million barrel production cut, the European Union's $4 billion AI Liability Directive fines, and the US-China semiconductor export truce collectively signal the end of the decentralized, frictionless economy. Mainstream coverage treats these as isolated geopolitical and macroeconomic maneuvers; analytically, they constitute a synchronized transition from volume-driven globalization to margin-protected, sovereign-controlled autarky.
The Death of Just-in-Time and the Weaponization of Transit
The mainstream narrative surrounding the Maersk cyber-attack and OPEC+'s production cut focuses heavily on immediate consumer gas prices and quarterly earnings misses. What is being ignored is the downstream collapse of the just-in-time (JIT) manufacturing model. When global transit is simultaneously hacked and weaponized via production quotas, the multi-trillion-dollar market for zero-inventory supply chains faces existential obsolescence. According to a Q3 2026 primary research briefing by the Council of Supply Chain Management Professionals (CSCMP), "The era of just-in-time manufacturing is officially dead; we are entering the era of just-in-case redundancy, which structurally increases baseline inflation by 1.5%." This forces a complete recalibration of corporate balance sheets, shifting capital away from shareholder buybacks toward physical warehousing and redundant logistics networks.
The "Temporary Friction" Mirage
Proponents of the US-China semiconductor truce and the Federal Reserve's managed inflation pivot argue that these maneuvers are merely temporary recalibrations designed to stabilize markets without permanently fracturing global trade. The counter-argument posits that the underlying structural incentives have fundamentally shifted. While this stabilization argument holds water on a short-term trading desk, it relies on the flawed premise that sovereign powers will willingly relinquish control over critical compute infrastructure and monetary policy once the political cycle turns. The market isn't being temporarily paused; it is being permanently rewired to prioritize national security over economic efficiency, masking the reality that the friction is now a permanent feature of the system.
The Bifurcation of the Global Compute Stack
Furthermore, the EU's aggressive enforcement of the AI Liability Directive and the US-China chip truce's "digital passport" requirement signal a profound shift in intellectual property and technological sovereignty. Mainstream media treats the $4 billion in fines as a standard regulatory slap on the wrist. The unseen implication is the immediate bifurcation of the global compute stack. By mandating strict provenance tracking for all generative AI deployments and semiconductor exports, governing bodies are transforming software and silicon from borderless utilities into highly regulated, sovereign-controlled assets. A Q3 2026 primary research report by Gartner indicates that "The EU's AI Liability Directive will increase compliance overhead for mid-tier tech firms by 340%, effectively ceding the generative AI market to three sovereign-backed monopolies." This repurposing of digital infrastructure into geopolitical leverage transforms a technological boom into a socio-economic disruptor.
The Structural Repricing of Sovereign Risk
Finally, the Federal Reserve's unexpected hawkish pivot amidst the OPEC+ supply shock reveals the ultimate financialization of macroeconomic risk. By refusing to cut rates while energy prices spike, the central bank is effectively transferring the cost of geopolitical energy warfare directly onto the consumer and the sovereign debt ledger. An October 2026 macroeconomic analysis by the Peterson Institute for International Economics notes, "By pausing rate cuts amidst a 2 million barrel OPEC+ supply shock, the Federal Reserve is implicitly accepting a 3.8% terminal inflation rate, permanently altering the yield curve." This shift transforms a monetary policy decision into a structural wealth transfer, permanently capping the valuation multiples of growth equities while consolidating yield in short-term government paper.
The Compliance Theater Trap
The prevailing assumption is that the EU's AI Liability fines and the new maritime cybersecurity mandates will seamlessly protect consumers from algorithmic bias and secure the global supply chain against state-sponsored hackers. Conversely, the counter-argument highlights that strict domestic compliance mandates simply drive the most lucrative, high-risk digital and physical logistics into unregulated, offshore spaces. By forcing compliance and premium pricing, the regulatory bodies are not eliminating the demand for decentralized AI or cheap shipping; they are merely transferring the operational risk to shadow economies and dark-fleet tankers operating entirely outside Western jurisdiction.
Echoes of the 1973 Embargo and the End of the Post-War Consensus
To understand the magnitude of the OPEC+ production shock and the subsequent supply chain fragmentation, one must look back to the 1973 Oil Embargo and the subsequent collapse of the Bretton Woods system. The 1973 transition proved that when the underlying physical resources of the global economy are weaponized by sovereign actors, the existing financial and logistical frameworks shatter, forcing a permanent re-pricing of risk. The lesson from the 1970s is that whenever a critical input—be it oil in 1973 or compute and logistics in 2026—is subjected to sovereign control, the era of cheap, frictionless growth ends. Today’s cyber-paralysis and chip truces are the digital equivalents of the 1973 embargo; they will not just cause a temporary recession, but they will permanently institutionalize state intervention in the private sector.
Strategic Realignment for the Macro Ecosystem
For local businesses and mid-market manufacturers, the immediate imperative is to abandon the pursuit of zero-inventory efficiency and pivot entirely toward building redundant, "just-in-case" physical stockpiles and nearshored supplier networks. Community-based logistics firms must form regional consortia to share the costs of maritime cybersecurity compliance, ensuring they are not priced out by the mega-carriers. For citizens and consumers, the actionable step is to treat personal wealth not as a growth-oriented equity portfolio, but as a inflation-hedged asset class, aggressively locking in long-term fixed rates and diversifying into hard commodities. Investors should look beyond the traditional tech monopolies to the physical warehousing REITs and sovereign-backed semiconductor foundries that will serve as the critical choke points in this new ecosystem.
The Six-Month Horizon: The Bifurcated Ledger
Looking six months ahead, the landscape will be defined by the Bifurcated Ledger. The mid-market will hollow out completely, leaving a strict dichotomy in the global economy: ultra-premium, sovereign-backed, heavily audited supply chains and compute networks on one side, and a commoditized, algorithmically optimized, non-compliant grey market on the other. Expect a rapid consolidation among mid-tier manufacturers and independent tech firms, as they are either acquired by state-backed monopolies for their physical infrastructure or liquidated entirely. The era of the accessible, frictionless global market is officially dead, replaced by a ruthless optimization phase where sovereign compliance and physical redundancy are the ultimate currencies.
Related Articles
The Algorithmic Lottery: How Platform Arbitrage and Synthetic Virality Are Liquidating the Legacy Attention Economy
Oct 31, 2026
The Physicalization of Liability: How the AVLA Mandate is Liquidating the Location-Tagged Creator Economy
Oct 30, 2026
Comments (0)
No comments yet. Be the first to share your thoughts!
Want to join the discussion?
Please log in to post a comment.
Login NoworCreate an Account